India is testing AI to build climate models to improve weather forecasting as torrential rains, floods and droughts proliferate across the vast country, a top weather official said. From a report: Global warming has triggered more intense clashes of weather systems in India in recent years, increasing extreme weather events, which the independent Centre for Science and Environment estimates have killed nearly 3,000 people this year. Weather agencies around the world are focussing on AI, which can bring down cost and improve speed, and which Britain’s Met Office says could “revolutionise” weather forecasting, with a recent Google-funded model found to have outperformed conventional methods.
Accurate weather forecasting is particularly crucial in India, a country of 1.4 billion people, many impoverished, and the world’s second-largest producer of rice, wheat and sugar. The India Meteorological Department (IMD) provides forecasts based on mathematical models using supercomputers. Using AI with an expanded observation network could help generate higher-quality forecast data at lower cost. The department expects the AI-based climate models and advisories it is developing to help improve forecasts, K.S. Hosalikar, head of climate research and services at IMD, told Reuters.
Google is adding some new bells and whistles to Chrome on the desktop that could potentially make the world’s most popular browser a bit faster and more secure. While these are not necessarily game-changing alterations, they’re significant enough that you may want to initiate a manual update rather than waiting for Chrome to automatically
Bad bosses, or managers who regularly disappoint you, are common. This disappointment you feel can be varied. Maybe you crave mentorship and you feel ignored, or you desire autonomy but you feel controlled. Or maybe you would just really appreciate your supervisor actually responding to your emails once in a while. You are not alone. This survey of 1,500 employees found that 24% of them felt they were working for the “worst manager they’ve ever had.” And the impacts of dealing with a bad boss can range anywhere from general job disengagement to affecting your sleep habits, your relationships with others, and even your self-worth.
That said, in my years of working with managers, I’ve never met one who intentionally set out to be bad at it. Most people in supervisory roles are doing their best with the skills, knowledge, energy, and focus they possess within the circumstances. Also, relationships with bosses are exactly that: a relationship. That means it takes more than one person to create the dynamic, so staff also bear some responsibility for maintaining a healthy and productive boss/employee relationship.
This means that if you work for a bad boss, you have some agency over how that relationship plays out by way of how you interact with and react to them. It’s important to avoid focusing on trying to change your boss or spend any time wishing your boss was someone else. Instead, accepting them for who they are is the first step. Then, you can focus on your own interactions with them.
Here are four types of bad managers, and a few tips on how to handle each one of them.
How to deal with a boss who is a micromanager
Micromanagers are famous for having a low tolerance for ambiguity. They resist letting employees make their own decisions and monitor work closely. Micromanagers do this because they need a lot of information to feel confident and prepared to deliver on their own work. Many micromanagers are also born from other micromanagers. Meaning, they behave this way because their boss does and so on up the company’s leadership pipeline.
In these instances, try letting go feeling like you’re not trusted. It’s probably not the case. Instead, give your boss what they need to be successful and effective at their work. Ask them how frequently they want to be updated and in what format. By all means, don’t withhold information from them. Also, be willing to examine your own behavior and correct it in the event you might be encouraging micromanagement. For more advice on working with micromanagers, see my full guide here.
How to deal with a boss who acts like a buddy
These are managers who seem to care more about what their team thinks of them than making tough decisions, delegating work, or holding others accountable. Often, “friend managers” have compromised their ability to act as a supervisor because they frequently engage socially with their team or exchange too much personal information with staff. When tough decisions have to be made, they are inappropriately influenced by social interactions, struggle with worry over how they are thought of by staff, or confide in some but not in others (creating unfair work environments).
If you work for a “friend manager,” the first step is to break up. Stop being friends with your manager. By remaining too friendly with your boss, you are actively contributing to all the challenges that are in play. If cutting ties cold turkey is too extreme, make a commitment to not discuss work when you hang out socially. But better yet, just stop hanging out socially. By creating distance, many find their job experience improves.
How to deal with the “lone wolf” boss
This is the non-manager of managers. They function as an individual contributor, solely focused on their own work and deliverables while still approving timecards and vacation requests. They seem to have little concern or focus on the development of the team. Some people love working for these bosses because they have ultimate freedom and autonomy. But if you’re someone looking for mentorship or the experience of being led with strategic direction, this supervisor leaves you feeling unfulfilled.
In these cases, identify what is missing from this boss relationship and find it elsewhere. If you’re looking for a manager who readily shares their own experience to guide you, find a mentor. (Here are a few tips on how to do that.) Or, if you’re looking for a boss to teach you skills, seek out professional development classes or consult with a tenured colleague. Ask them for advice on career advancement. These bosses aren’t the worst to work for, so you might also just enjoy the freedom they afford.
How to deal with a boss who is a jerk
This is maybe the worst type of boss to work for: the jerk. These managers lack self-awareness and behave in ways that can be disrespectful and hurtful. These are the bosses who are very difficult to accept for who they are; they are easy to just plain dislike.
In theses cases, first try to envision them as someone other than your boss. Think about them as a son or as a daughter. Maybe they are parents or volunteers at a local nonprofit. Here’s the thing, jerks are jerks for a reason; they routinely behave badly. But, they are also human. Sometimes, finding their humanity can give you the patience to endure their antics. Then, inventory all the benefits or positive aspects of working for them or the company. Post that list so that you are reminded regularly. If their behavior is unethical or illegal, consider reporting them via your company’s policies. And, by all means, look for another job if those strategies aren’t fruitful.
Bad managers are common but the good news is that they aren’t everywhere. The same survey that found almost a quarter of employees were working for “the worst manager they’ve ever had” also found that 64% were working for the best boss they ever had. Great bosses are out there. If you’re working for one that leaves you unsatisfied, either develop your strategies to interact with them or accept that it might be time to find a new manager.
If you haven’t heard, the popular budgeting app Mint is about to go away. Parent company Intuit will shut down the service on March 24, 2024. The company suggests folks migrate to its other personal finance app, Credit Karma. Mint had 3.6 million active users as of 2021, according to Bloomberg, and I’m one of them. I use the app to track all of my accounts in one place without having to log into too many disparate banking apps. But I’ve also used it to monitor my credit score, stick to a monthly budget, and set goals like building a rainy-day fund or paying down my mortgage faster.
Intuit has not commented on whether it intends to fold Mint’s budgeting features into Credit Karma but as it stands, Credit Karma is not a Mint substitute: It’s meant to monitor your credit and, Intuit hopes, steer you toward credit cards and various other financial products.
So, over the past month, I’ve downloaded a good half-dozen competing money apps to see if any might cut it as a permanent Mint replacement. What follows is the guide I would have wanted to read: a comparison of budgeting apps that promise to track your net worth and spending in one place. Join me as I fall down a rabbit hole.
How we tested
First, I had to do some research. To find a list of apps to test, I consulted trusty ol’ Google (and even trustier Reddit); read reviews of popular apps on the App Store; and also asked friends and colleagues what budget tracking apps they might be using. Some of the apps I found were free, just like Mint. These, of course, show loads of ads (excuse me, “offers”) to stay in business. But most of the available apps require paid subscriptions, with prices typically topping out around $100 a year, or $15 a month. (Spoiler: My top pick is cheaper than that.)
Since this guide is meant to help Mint users find a permanent replacement, any services I chose to test needed to do several things: import all of your account data into one place; offer budgeting tools; and track your spending, net worth and credit score. Except where noted, all of these apps are available for iOS, Android and on the web.
Once I had my shortlist of six apps, I got to work setting them up. For the sake of thoroughly testing these apps (and remember, I really was looking for a Mint alternative myself), I made a point of adding every account to every tracking app, no matter how small or immaterial the balance. What ensued was a veritable Groundhog Day of two-factor authentication. Just hours of entering passwords and one-time passcodes, for the same banks half a dozen times over. Hopefully, you only have to do this once.
What is Plaid and how does it work?
Dana Wollman / Engadget
Each of the apps I tested uses the same underlying network, called Plaid, to pull in financial data, so it’s worth explaining up top what it is and how it works. Plaid was founded as a fintech startup in 2013 and is today the industry standard in connecting banks with third-party apps. Plaid works with over 12,000 financial institutions across the US, Canada and Europe. Additionally, more than 8,000 third-party apps and services rely on Plaid, the company claims.
To be clear, you don’t need a dedicated Plaid app to use it; the technology is baked into a wide array of apps, including the budget trackers I tested for this guide. Once you find the “add an account” option in whichever one you’re using, you’ll see a menu of commonly used banks. There’s also a search field you can use to look yours up directly. Once you find yours, you’ll be prompted to enter your login credentials. If you have two-factor authentication set up, you’ll need to enter a one-time passcode as well.
As the middleman, Plaid is a passthrough for information that may include your account balances, transaction history, account type and routing or account number. Plaid uses encryption, and says it has a policy of not selling or renting customer data to other companies. However, I would not be doing my job if I didn’t note that in 2022 Plaid was forced to pay $58 million to consumers in a class action suit for collecting “more financial data than was needed.” As part of the settlement, Plaid was compelled to change some of its business practices.
In a statement provided to Engadget, a Plaid spokesperson said the company continues to deny the allegations underpinning the lawsuit and that “the crux of the non-financial terms in the settlement are focused on us accelerating workstreams already underway related to giving people more transparency into Plaid’s role in connecting their accounts, and ensuring that our workstreams around data minimization remain on track.”
How to import your financial data from Mint
If only importing data from Mint were as easy as entering your credentials from inside your new budgeting app and hitting “import.” In fact, any app that advertises the ability to port over your stats from Mint is just going to have you upload a CSV file of transactions and other data.
To download a CSV file from Mint, do the following:
Sign into Mint.com and hit Transactions in the menu on the left side of the screen.
Select an account, or all accounts.
Scroll down and look for “export [number] transactions” in smaller print.
Your CSV file should begin downloading.
Note: Downloading on a per-account basis might seem more annoying, but could help you get set up on the other side, if the app you’re using has you importing transactions one-for-one into their corresponding accounts.
The best budgeting app overall: Quicken Simplifi
No pun intended, but what I like about Quicken Simplifi is its simplicity. Whereas other apps try to distinguish themselves with dark themes and customizable emoji, Simplifi has a clean user interface, with a landing page that you just keep scrolling through to get a detailed overview of all your stats. These include your top-line balances; net worth; recent spending; upcoming recurring payments; a snapshot of your spending plan; top spending categories; achievements; and any watchlists you’ve set up. You can also set up savings goals elsewhere in the app. I also appreciate how it offers neat, almost playful visualizations without ever looking cluttered. I felt at home in the mobile and web dashboards after a day or so, which is faster than I adapted to some competing services (I’m looking at you, YNAB and Monarch).
Getting set up with Simplifi was mostly painless. I was particularly impressed at how easily it connected to Fidelity; not all budget trackers do, for whatever reason. This is also one of the only services I tested that gives you the option of inviting a spouse or financial advisor to co-manage your account.
Dana Wollman / Engadget
In practice, Simplifi miscategorized some of my expenses, but nothing out of the ordinary compared to any of these budget trackers. As you’re reviewing transactions, you can also mark if you’re expecting a refund, which is a unique feature among the services I tested. Simplifi also estimated my regular income better than some other apps I tested. Most of all, I appreciated the option of being able to categorize some, but not all, purchases from a merchant as recurring. For instance, I can add my two Amazon subscribe-and-saves as recurring payments, without having to create a broad-strokes rule for every Amazon purchase.
The budgeting feature is also self-explanatory. Just check that your regular income is accurate and be sure to set up recurring payments, making note of which are bills and which are subscriptions. This is important because Simplifi shows you your total take-home income as well as an “income after bills” figure. That number includes, well, bills but not discretionary subscriptions. From there, you can add spending targets by category in the “planned spending” bucket. Planned spending can also include one-time expenditures, not just monthly budgets. When you create a budget, Simplifi will suggest a number based on a six-month average.
Not dealbreakers, but two things to keep in mind as you get started: Simplifi is notable in that you can’t set up an account through Apple or Google. There is also no option for a free trial, though Quicken promises a “30-day money back guarantee.”
The best budgeting app (runner-up): Monarch Money
Monarch Money grew on me. My first impression of the app, which was founded by a former Mint product manager, was that it’s more difficult to use than others on this list, including Simplifi, NerdWallet and Copilot. And it is. Editing expense categories, adding recurring transactions and creating rules, for example, is a little more complicated than it needs to be, especially in the mobile app. (My advice: Use the web app for fine-tuning details.) Monarch also didn’t get my income right; I had to edit it.
Once you’re set up, though, Monarch offers an impressive level of granularity. In the budgets section, you can see a bona fide balance sheet showing budgets and actuals for each category. You’ll also find a forecast, for the year or by month. And recurring expenses can be set not just by merchant, but other parameters as well. For instance, while most Amazon purchases might be marked as “shopping,” those for the amounts of $54.18 or $34.18 are definitely baby supplies, and can be automatically marked as such each time, not to mention programmed as recurring payments. Weirdly, though, there’s no way to mark certain recurring payments as bills, specifically.
Dana Wollman / Engadget
The mobile app is mostly self-explanatory. The main dashboard shows your net worth; your four most recent transactions; a month-over-month spending comparison; income month-to-date; upcoming bills; an investments snapshot; a list of any goals you’ve set; and, finally, a link to your month-in-review. That month-in-review is more detailed than most, delving into cash flow; top income and expense categories; cash flow trends; changes to your net worth, assets and liabilities; plus asset and liability breakdowns.
On the main screen, you’ll also find tabs for accounts, transactions, cash flow, budget and recurring. Like many of the other apps featured here, Monarch can auto-detect recurring expenses and income, even if it gets the category wrong. (They all do to an extent.) Expense categories are marked by emoji, which you can customize if you’re so inclined.
Monarch Money uses a combination of Plaid and Finicity, a competing network owned by Mastercard. Similar to NerdWallet, I found myself completing two-factor authentication every time I wanted to get past the Plaid screen to add another account. Notably, Monarch is the only other app I tested that allows you to grant access to someone else in your family — likely a spouse or financial advisor. Monarch also has a Chrome extension for importing from Mint, though really this is just a shortcut for downloading a CSV file, which you’ll have to do regardless of where you choose to take your Mint data.
The best up-and-comer: Copilot Money
Copilot Money might be the best-looking budget tracker I tested. It also has the distinction of being exclusive to iOS and Macs — at least for now. Andres Ugarte, the company’s CEO, has publicly promised that Android and web apps are coming in 2024 (more likely the second half of the year, Ugarte tells me). But until it follows through, I can’t recommend Copilot for most people with so many good competitors out there.
Copilot Money for Web and Android!
Thanks to the support from our users, and the overwhelming positive reception we’re seeing from folks migrating from Mint, we can now say that we’ll be building @copilotmoney for Web and Android with a goal to launch in 2024.
There are other features that Copilot is missing, which I’ll get into. But it is promising, and one to keep an eye on. It’s just a fast, efficient, well designed app, and Android users will be in for a treat when they’ll finally be able to download it. It makes good use of colors, emoji and graphs to help you understand at a glance how you’re doing on everything from your budgets to your investment performance to your credit card debt over time. In particular, Copilot does a better job than almost any other app of visualizing your recurring monthly expenses.
Behind those punchy colors and cutesy emoji, though, is some sophisticated performance. Copilot’s AI-powered “Intelligence” gets smarter as you go at categorizing your expenses. (You can also add your own categories, complete with your choice of emoji.) It’s not perfect. Copilot miscategorized some purchases (they all do), but it makes it easier to edit than most. On top of that, the internal search feature is very fast; it starts whittling down results in your transaction history as soon as you begin typing.
Dana Wollman / Engadget
Copilot is also unique in offering Amazon and Venmo integrations, allowing you to see transaction details. With Amazon, this requires just signing into your Amazon account via an in-app browser. For Venmo, you have to set up fwd@copilot.money as a forwarding address and then create a filter, wherein emails from venmo@venmo.com are automatically forwarded to fwd@copilot.money.
While the app is heavily automated, I still appreciate that Copilot marks new transactions for review. It’s a good way to both weed out fraudulent charges, and also be somewhat intentional about your spending habits.
Because the app is relatively new (it launched in early 2020), the company is still catching up to the competition on some table-stakes features. Ugarte told me that his team is almost done building out a detailed cash flow section, which could launch before the end of 2023, but more likely in early 2024. On its website, Copilot also promises a raft of AI-powered features that build on its current “Intelligence” platform, the one that powers its smart expense categorization. These include “smart financial goals,” natural language search, a chat interface, forecasting and benchmarking. That benchmarking, Ugarte tells me, is meant to give people a sense of how they’re doing compared to other Copilot users, on both spending and investment performance. Most of these features should arrive in the new year.
Copilot does a couple interesting things for new customers that distinguish it from the competition. There’s a “demo mode” that feels like a game simulator; no need to add your own accounts. The company is also offering two free months with RIPMINT — a more generous introductory offer than most. When it finally does come time to pony up, the $7.92 monthly plan is cheaper than some competing apps, although the $95-a-year-option is in the same ballpark.
The best free budgeting app: NerdWallet
You may know NerdWallet as a site that offers a mix of personal finance news, explainers and guides. I see it often when I google a financial term I don’t know and sure enough, it’s one of the sites I’m most likely to click on. As it happens, NerdWallet also has the distinction of offering one of the only free budget tracking apps I tested. In fact, there is no paid version; nothing is locked behind a paywall. The main catch: There are ads everywhere. To be fair, the free version of Mint was like this, too.
Even with the inescapable credit card offers, NerdWallet has a clean, easy-to-understand user interface, which includes both a web and a mobile app. The key metrics that it highlights most prominently are your cash flow, net worth and credit score. (Of note, although Mint itself offered credit score monitoring, most of its rivals do not.) I particularly enjoyed the weekly insights, which delve into things like where you spent the most money or how much you paid in fees — and how that compares to the previous month. Because this is NerdWallet, an encyclopedia of financial info, you get some particularly specific category options when setting up your accounts (think: a Roth or non-Roth IRA).
Dana Wollman / Engadget
As a budgeting app, NerdWallet is more than serviceable, if a bit basic. Like other apps I tested, you can set up recurring bills. Importantly, it follows the popular 50/30/20 budgeting rule, which has you putting 50% of your budget toward things you need, 30% toward things you want, and the remaining 20% into savings or debt repayments. If this works for you, great — just know that you can’t customize your budget to the same degree as some competing apps. You can’t currently create custom spending categories, though a note inside the dashboard section of the app says “you’ll be able to customize them in the future.” You also can’t move items from the wants column to “needs” or vice versa but “In the future, you’ll be able to move specific transactions to actively manage what falls into each group.” A NerdWallet spokesperson declined to provide an ETA, though.
Lastly, it’s worth noting that NerdWallet had one of the most onerous setup processes of any app I tested. I don’t think this is a dealbreaker, as you’ll only have to do it once and, hopefully, you aren’t setting up six or seven apps in tandem as I was. What made NerdWallet’s onboarding especially tedious is that every time I wanted to add an account, I had to go through a two-factor authentication process to even get past the Plaid splash screen, and that’s not including the 2FA I had set up at each of my banks. This is a security policy on NerdWallet’s end, not Plaid’s, a Plaid spokesperson says.
Precisely because NerdWallet is one of the only budget trackers to offer credit score monitoring, it also needs more of your personal info during setup, including your birthday, address, phone number and the last four digits of your social security number. It’s the same with Credit Karma, which also does credit score monitoring.
Related to the setup process, I found that NerdWallet was less adept than other apps at automatically detecting my regular income. In my case, it counted a large one-time wire transfer as income, at which point my only other option was to enter my income manually (which is slightly annoying because I would have needed my pay stub handy to double-check my take-home pay).
Budgeting apps we also tested
YNAB
YNAB is, by its own admission, “different from anything you’ve tried before.” The app, whose name is short for You Need a Budget, promotes a so-called zero-based budgeting system, which forces you to assign a purpose for every dollar you earn. A frequently used analogy is to put each dollar in an envelope; you can always move money from one envelope to another in a pinch. These envelopes can include rent and utilities, along with unforeseen expenses like holiday gifts and the inevitable car repair. The idea is that if you budget a certain amount for the unknowns each month, they won’t feel like they’re sneaking up on you.
Importantly, YNAB is only concerned with the money you have in your accounts now. The app does not ask you to provide your take-home income or set up recurring income payments (although there is a way to do this). The money you will make later in the month through your salaried job is not relevant, because YNAB does not engage in forecasting.
The app is harder to learn than any other here, and it requires more ongoing effort from the user. And YNAB knows that. Inside both the mobile and web apps are links to videos and other tutorials. Although I never quite got comfortable with the user interface, I did come to appreciate YNAB’s insistence on intentionality. Forcing users to draft a new budget each month and to review each transaction is not necessarily a bad thing. As YNAB says on its website, “Sure, you’ve got pie charts showing that you spent an obscene amount of money in restaurants — but you’ve still spent an obscene amount of money in restaurants.” I can see this approach being useful for people who don’t tend to have a lot of cash in reserve at a given time, or who have spending habits they want to correct (to riff off of YNAB’s own example, ordering Seamless four times a week).
My colleague Valentina Palladino, knowing I was working on this guide, penned a respectful rebuttal, explaining why she’s been using YNAB for years. Perhaps, like her, you have major savings goals you want to achieve, whether it’s paying for a wedding or buying a house. I suggest you give her column a read. For me, though, YNAB’s approach feels like overkill.
PocketGuard
PocketGuard is one of the only reputable free budget trackers I found in my research. Just know it’s far more restricted at the free tier than NerdWallet or Mint. In my testing, I was prompted to pay after I attempted to link more than two bank accounts. So much for free, unless you keep things simple with one cash account and one credit card. When it comes time to upgrade to PocketGuard Plus, you have three options: pay $7.99 a month, $34.99 a year or $79.99 for a one-time lifetime license. That lifetime option is actually one of the few unique selling points for me: I’m sure some people will appreciate paying once and never having to, uh, budget for it again.
From the main screen, you’ll see tabs for accounts, insights, transactions and the “Plan,” which is where you see recurring payments stacked on top of what looks like a budget. The main overview screen shows you your net worth, total assets and debts; net income and total spending for the month; upcoming bills; a handy reminder of when your next paycheck lands; any debt payoff plan you have; and any goals.
Dana Wollman / Engadget
Like some other apps, including Quicken Simplifi, PocketGuard promotes an “after bills” approach, where you enter all of your recurring bills, and then PocketGuard shows you what’s left, and that’s what you’re supposed to be budgeting: your disposable income. Obviously, other apps have a different philosophy: take into account all of your post-tax income and use it to pay the bills, purchase things you want and maybe even save a little. But in PocketGuard, it’s the “in your pocket” number that’s most prominent. To PocketGuard’s credit, it does a good job visualizing which bills are upcoming and which ones you’ve already paid.
PocketGuard has also publicly committed to adding some popular features in early 2024. These include rollover budgeting in January 2024, categorization rules in February and shared household access in March.
Dana Wollman / Engadget
Although PocketGuard’s UI is easy enough to understand, it lacks polish. The “accounts” tab is a little busy, and doesn’t show totals for categories like cash or investments. Seemingly small details like weirdly phrased or punctuated copy occasionally make the app feel janky. More than once, it prompted me to update the app when no updates were available. The web version, meanwhile, feels like the mobile app blown up to a larger format and doesn’t take advantage of the extra screen real estate.
Of note, although PocketGuard does work with Plaid, its primary bank-connecting platform is actually Finicity. Setting up my accounts through Finicity was mostly a straightforward process. I did encounter one hiccup: Finicity would not connect to my SoFi account. I was able to do it through Plaid, but PocketGuard doesn’t make it easy to access Plaid in the app. The only way, as far as I can tell, is to knowingly search for the name of a bank that isn’t available through Finicity, at which point you get the option to try Plaid instead. Like I said: the experience can be janky.
This article originally appeared on Engadget at https://www.engadget.com/the-best-budgeting-apps-to-replace-mint-143047346.html?src=rss
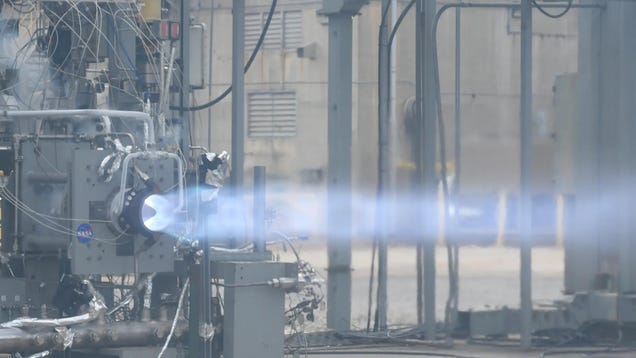
NASA just put its new propulsion system to the test, powering a 3D-printed rotating detonation rocket engine for a sustained burn that lasted three times as long as the first test.
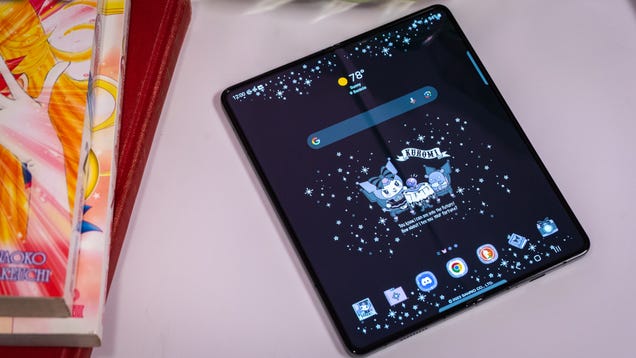
Last year, I mused over whether foldable smartphones would ever be affordable. I wanted to see them take off after falling in love with the Galaxy Z Fold 4. This year, I got my answer. It’s a resounding “No,” especially with the foldable market as it is right now. Even with the recently launched Motorola Razr, a flip…
Happy holidays! Hopefully you’ll be able to take a break from the upcoming festivities to enjoy some gaming. Should you find yourself at a loss of what to play, we’ve got a few recs.
One of the new features to look forward to with the upcoming Linux 6.8 kernel cycle is the merging of the experimental “Xe” Intel kernel graphics driver. This driver has been in development for quite a while but has reached the state now at which Intel is comfortable with developing it further while in the mainline kernel tree.
The 10 words below are commonly mispronounced in English. The first five are the top results from Google’s auto-fill for the phrase “How do I pronounce…” The rest are words that people often don’t know they’re messing up, so would be unlikely to search up on the web.
I’m no prescriptivist—words are yours to do with as you will, so pronounce ‘em however you like. “Correct” pronunciations are just what we call the way words are usually spoken according to the general consensus of English speakers. But there’s no governing body—if enough people pronounce a word “wrong” it stops being wrong, so keep saying “fried skrimp” or “Anartica” like I do.
Gyro
I’m starting with a tricky one. “Gyro” is either a shortened form of “gyroscope” or the name of a Greek lamb sandwich.
In the unlikely event that you’re talking about gyroscopes enough to need to shorten the word, it’s pronounced “jeye-roh.” The greek sandwich, according to Websters, is called a “yee-roh” or a “zhir-roh.” It’s rhymes with “hero.”
Interestingly, the Greek word for “to turn” is the root of the word for both the sandwich and the machine, but the terms came into the language at different times, so we don’t say them the say way.
Açaí
The berries from the Açaí palm tree that grows in South America have become popular enough that you may be called upon to say their name at brunch. If so, it’s pronounced aa-saa-ee. It doesn’t seem to make sense based on the spelling, but those accents over the “c” and the “I” tell the story: The word’s root is from Portuguese, and the accent over the “c” means “soft s sound,” and the mark over the “i” means “long e.”
Nguyen
“Nguyen” is a common last name in Vietnam, and Vietnamese is a little tricky for English speakers. We aren’t used to starting words with an “ng” sound. To add complexity: “Nguyen” is pronounced differently in different parts of Vietnam. In south Vietnam, it’s pronounced close to “win” or “wen.” In the north, they’re more likely to say something like “nuh-win,” but as close to one syllable as possible.
Gif
It’s pronounced “Jif” like the peanut butter, according to Steve Wilhite, the creator of the Graphics Interchange Format. Or it’s pronounced with the hard “g” sound because that makes more sense to you. There is no right answer.
Worcestershire
Worcestershire is a county in England where they invented a delicious condiment in the 1830s. It’s pronounced wu-stuh-shr. It’s not pronounced “Wor-chest-tir-shire.”
Phở
This Vietnamese noodle soup is pronounced “fuuh,” according to Websters, but “foe” seems to be catching on fast, at least if you’re an English speaker. Neither is exactly how Vietnamese people pronounce it, because “phở” contains a sound English doesn’t include.
Library
It’s not “lie-berry” or “lie-bear-y” It’s “llai-breh-ree.” But if you say it quickly without careful enunciation, it will sound like “lie-bree” anyway. It’s just an awkward word because of that middle syllable.
Often
That “t” in “often” should not be there. It’s not in the word when you say it, because it’s pronounced “aa-fn.” See also: “castle,” “mortgage,” “listen,” “soften,” and a slew of other words with silent t’s.
Niche
“Niche” can be pronounced “neesh” (rhymes with “sheesh”) or it can be pronounced “nich” (rhymes with “pitch.”), “Neesh” is a newer pronunciation. “nich” is the classic. But both are fine.
Arctic
It’s annoying, but “they” say you’re supposed to pronounce the hard “c”: So it’s “aark-tuhk,” not “ar-tuhk.” The same rule applies to “Antarctic,” which also has an inconvenient “t” sound you’re supposed to pronounce too.
This wasn’t always the case. The word used to be spelled “artic” and pronounced “ar-tik” but it was changed in the 17th century to match the Latin spelling. It’s all a mess.
Cache
This is an easy one! A “cache” is a group of hidden things. It’s pronounced “kash.” Some people say “kaysh,” probably because of the ending “e.” Some people say “kash-ay,” but. if you do that, you’re using the word “cachet,” which means “prestige.”
Forte
“Forte” (a person’s strong suit) has no agreed-upon pronunciation. You can say “fort.” Or you can say “for-tay,” or “for-tay.” No matter how you say it, someone will think you’re wrong.
But if you’re using “forte” to talk about the musical notation for “play loudly,” it’s always “for-tay”
PlayStation will no longer be removing over 1,300 Discovery TV shows from its platform next month. From a report: Sony had previously announced that users will not be able to watch Discovery content on PlayStation from December 31, even if they had already purchased it. However, the firm now says that due to an ‘updated licensing agreement’ with Warner Bros — which owns the Discovery brand — consumers will now be able to access their previously purchased shows ‘for at least the next 30 months.’
Latest version of Mozilla’s web browser brings something different depending on your machineVersion 121 of Mozilla’s Firefox web browser, released yesterday, has changes that affect Linux, Windows, and Mac users differently.…
The idea of declaring “email bankruptcy”—just deleting all the emails in your inbox past a certain date—is so popular, it has its own Wikipedia entry. And it goes beyond email: Declaring a personal bankruptcy and mass-deleting games, movies, and e-books you fear you’ll never play, watch, or read is a common practice with proponents far and wide (including some right here at Lifehacker). But declaring bankruptcy is such a drastic step. What if you tried inbox amnesty instead?
What is inbox amnesty?
The idea for inbox amnesty comes from Lifehacker’s health editor, Beth Skwarecki, who advocates for achieving inbox zero by selecting all your emails and archiving them, instead of deleting them. “BOOM,” she says. “You have inbox zero and will do better in the future.”
While there are tricks you can employ to manage your inbox in real time and keep the number of unread messages down (like the “one touch” rule), there will still be times when your inbox gets unruly. That doesn’t bother some people, but the ever-increasing number in the notifications badge makes others feel like they’re losing their minds. If that’s you, declare inbox amnesty and just start over.
Why inbox amnesty is better than inbox bankruptcy
While inbox amnesty and bankruptcy both rely on the same idea—nuking all the emails and starting again, determined not to let the unreads get out of hand—there is one key difference: Amnesty doesn’t destroy the emails forever, it just marks them as read and tucks them away, out of sight.
This means you can go back into that archive if you need to, finding contact information or threads that you might actually need to follow up on in the future. If you go bankrupt and nuke them all, you won’t be able to refer to anything from the past—and you just know something will come up that requires you to look at an older email you no longer have.
You can set a reminder for yourself to fully delete your archived messages after six months if they don’t become necessary, but as long as they’re not clogging up too much of your storage, feel free to hold onto them in case of emergency.
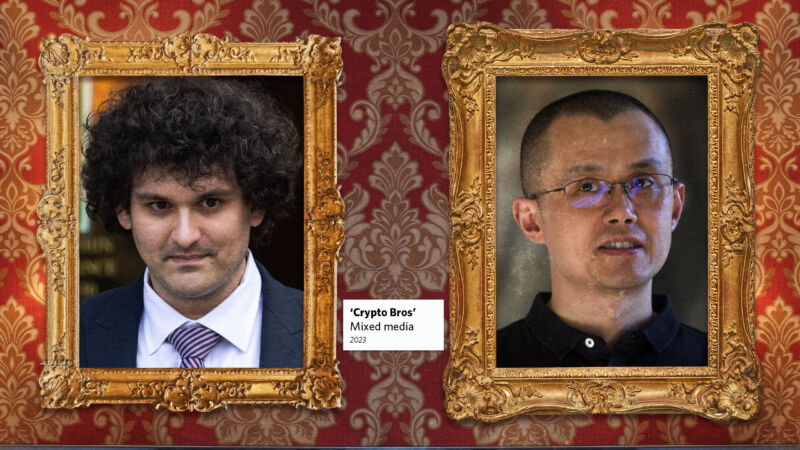
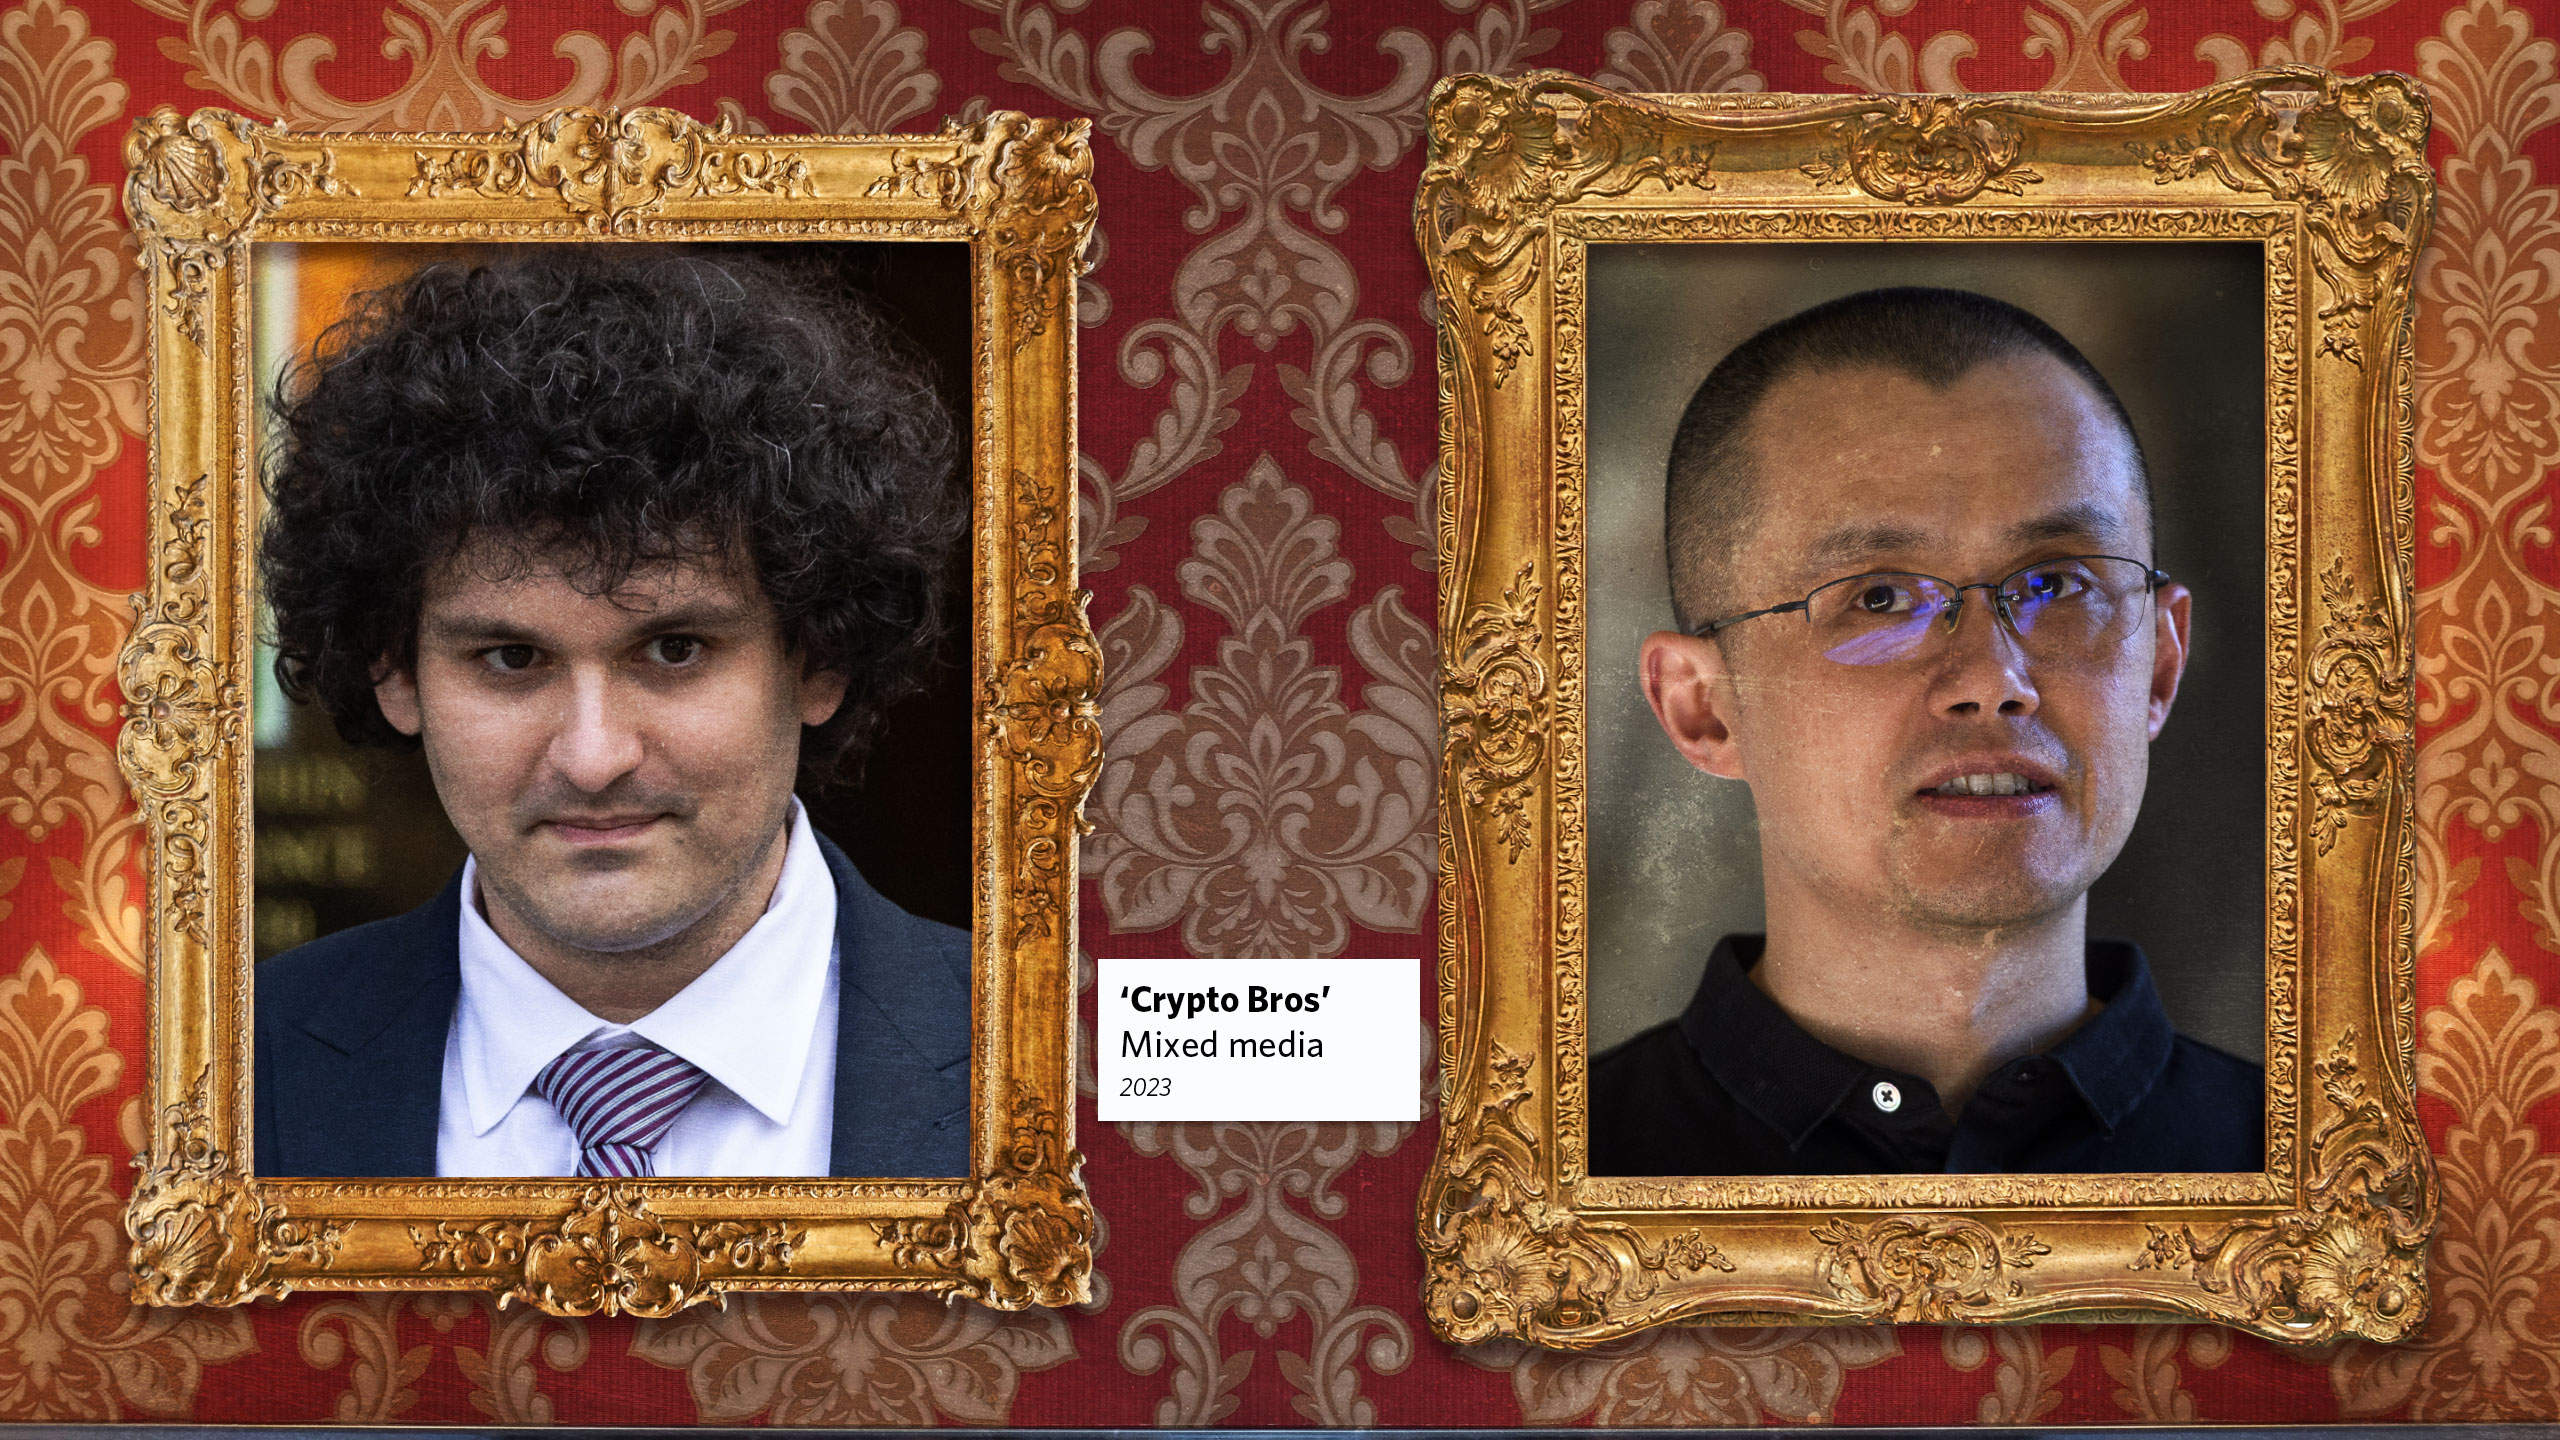
Looking back, 2023 will likely be remembered as the year of the fallen crypto bro.
While celebrities like Kim Kardashian and Matt Damon last year faced public backlash after shilling for cryptocurrency, this year’s top headlines traced the downfalls of two of the most successful and influential crypto bros of all time: FTX co-founder Sam Bankman-Fried (often referred to as SBF) and Binance founder Changpeng Zhao (commonly known as CZ).
At 28 years old, Bankman-Fried made Forbes’ 30 Under 30 list in 2021, but within two short years, his recently updated Forbes profile notes that the man who was once “one of the richest people in crypto” in “a stunning fall from grace” now has a real-time net worth of $0.
Remember when you were little and asking questions was easy? You weren’t expected to know everything, and everyone understood that you would need help sometimes. Yet now that you’re a parent helping your own kids, asking for help yourself seems so much harder—even when you feel just as lost and in need of guidance as you did all those years ago.
“At a young age, you asked incredibly hard questions without fear or hesitation, and with conviction,” writes Laura Fredericks in her book Hard Asks Made Easy: How to Get Exactly What You Want. “The ask has always been in you.” Figuring out how to unlock “the ask” as an adult can be surprisingly challenging, but doing so pays dividends.
Fredricks’ tips for asking are applicable to big asks like talking to an employer about needing more flexible hours, or asks that just feel big, like approaching a parent acquaintance for a favor. And any parenting situation that overwhelms you is an opportunity to ask for help, whether it’s from your partner, your children, family members, or other members of the community. Here’s how to ask for help as an overwhelmed parent.
There are four types of “askers”
Fredericks identifies four types of “askers.” You can take her quiz to identify your type here. And figuring that out can help you better ask for help when you need it.
Here’s an overview of advantages, drawbacks, and tips for each type of aske.
The Negotiator
This asker wants everyone to be at ease and is well-prepared with attention to detail. Their style may leave the person they ask feeling too at ease, like the request wasn’t that important after all. This type of asker should try to be more direct, dial back the excessively agreeable nodding and smiling, and address conflict calmly instead of trying to smooth things over.
In practice, that might look like this: The Negotiator might want to tell her employer, “I think we’re on the same page that it’s more efficient for me to work from home while my child is out of school than to use PTO and lose a day to work on the presentation, right?” A more direct approach would be better: “We were talking about how important it is to get the presentation done this week, and I can manage that. I do need some flexibility Thursday, since my daughter will be home from school. Can I work from home Thursday to finish my part, and we can finalize Friday?”
The Empathizer
This asker spends most of their asking time listening and putting themselves in the other person’s position. They may be so other-focused they end up leaving themself (and the importance of their need for help) out of the equation. Empathizers, remember you are asking on behalf of yourself, yes, but also your family group. Try to shift focus away from your empathy for how it will inconvenience the person you’re asking, and toward the people who will benefit from their aid.
For example, the Empathizer needs her husband to pick up the kids while she goes to urgent care for a sudden illness. She can tell right away he’s had a busy day and her empathy gets in the way. She might say, “I can tell you’re so busy at work right now. I hoped you could pick up the kids while I go to the doctor, but maybe it would be easier for me to find an urgent care with later hours so I can go after you get home.” A better approach: “I know you are having a rough day. It’s not great timing, but I really need you to pick up the kids so I can see the doctor and start feeling better. If not, tomorrow might be even harder.”
The Presenter
This asker draws attention, is entertaining and interesting, works on developing relationships, but asks indirectly. In fact, it may not be totally clear they are asking for something. Fredricks suggests speaking 25% of the time and listening 75%. Be careful not to dominate with your personality, and don’t bury your request in a wordy speech.
Here’s an example: The Presenter hits the PTO meeting with waves, smiles, and jokes for everyone. He tells everyone about the Fall Festival plan, how fun it’s going to be, that he is going to judge the pumpkin contest. At the end of the meeting, the volunteer sign up sheet is empty because he failed to emphasize how everyone else’s contribution of time and supplies would be crucial to a successful event. To be more effective, the Presenter could jazz everyone up with his enthusiasm, mention how their individual skills would help with the project, and ask directly for a commitment to volunteer.
The Charmer
This asker captures attention with their words, story, and persuasion. However, they may come off as too direct. Charmers should get to know people with open ended questions, be aware of a too strong or too direct tone (which may seem aggressive), and word requests so they are more personal and less direct.
Here’s an example: The Charmer needs a new babysitter ASAP. At dance class, she tells the other moms an amusing story about her old sitter moving on, last minute tickets to a concert, and her dilemma of finding childcare. She hands each parent a notecard, saying, “Write down names and numbers of your best sitters so I can call everyone tonight!” No big deal, but it feels kind of like a gun-to-your-head situation. Instead, the Charmer could send a polite and simple text to her parent contacts saying, “Hi, long story, but I need a babysitter tomorrow. Is there anyone you would recommend?”
How to ask for help and get the answer you want
Be prepared. Select the right environment to ask for a favor. Face-to-face might be best for a really personal or emotional request, like asking your partner to help you find the time, money, and energy to see a therapist for burnout; you’ll get lots of body language feedback, but in-person may be hard to schedule for a last-minute request. A phone call is convenient and quick, but lacking in personal connection. A text is direct and simple, but you have to be very conscious of your tone; use text for quick requests from people you know well, like asking a friend if you can borrow their backyard movie screen for the weekend.
Be personal. Be aware of the interests, motivations, and lifestyle of the person you’re asking and how those things could impact their response. For example, if your want your kid’s help to prepare for visitors, emphasize how much fun they are going to have with Aunt Hope. If they help you make the bed, they can arrange an army of stuffed animal to keep her company.
Be present. During the asking conversation, be sure to really listen to the other person and stay present.
Format asks in two sentences, and one question. “This will prevent you from over-asking your ask or making your ask too confusing for the person to make a decision,” Fredricks wrote. Try this: Sentence 1: Acknowledge and empathize with the person you are asking for help. Sentence 2: Explain why you need help. Question: Ask how you can solve the need together. For example, “I appreciate you cleaning up the backyard this weekend — it was so hot. I want us to be able to spend more time out there as a family. Would you figure out how to get us some some of those big shades for the patio?”
Anticipate their responses. For big asks like requesting a raise, think through what they could say and how you would respond to each answer. Fredricks suggests you actually write all this down to build confidence in how you’ll respond.
What to do when the answer is “no”
Fredericks shares three mantras to help you accept a “no.”
“No” now is not “Never later.”
“No” now is an invitation to keep in touch with them.
“No” is an answer, one far better than never receiving a response.
If possible, find out why they said no, so you can know if they are a person you might come to for help at another time. Parenting is a long haul, and there will be more opportunities for people who care about you to help out.
“Finally, if you just cannot find your way to try these responses, or it is just not your style to do so, think of this. You have a definitive answer” Fredricks wrote. “It is worse, far worse, not to receive an answer and go chasing after it with multiple follow-ups, eating away at your time, than to have your answer. They actually did you a favor. They responded.”
More than anything, you need to get comfortable asking for help
Parenthood is often overwhelming, from managing schedules to illness to dealing with emotions and relationships. Thinking you have to do it all by yourself is just an added stressor in the equation.
Sometimes when I’m overwhelmed, just making a list of people I could ask for help is a relief. Start with being brave and confident enough to ask for help, then let people know you are willing to offer help in return, and before you know it, you’re building a whole supportive parenting network.
When you drop money in the bank, it looks like it’s just sitting there, ready for you to withdraw. In reality, your institution makes money on your money by lending it elsewhere, including to the fossil fuel companies driving climate change, as well as emissions-heavy industries like manufacturing.
So just by leaving money in a bank account, you’re unwittingly contributing to worsening catastrophes around the world. According to a new analysis, for every $1,000 dollars the average American keeps in savings, each year they indirectly create emissions equivalent to flying from New York to Seattle. “We don’t really take a look at how the banks are using the money we keep in our checking account on a daily basis, where that money is really circulating,” says Jonathan Foley, executive director of Project Drawdown, which published the analysis. “But when we look under the hood, we see that there’s a lot of fossil fuels.”
Generative artificial intelligence is everywhere you look these days, including on the web: advanced predictive text bots such as ChatGPT can now spew out endless reams of text on every topic imaginable and make all this written content natural enough that it could plausibly have been written by a human being.
Along with a countdown showing the next Unpacked will be on January 17, leaker Evan Blass shared a spec sheet that purports to break down the components of the Galaxy S24 lineup. Just like the S23 (pictured above), expect three Galaxy devices: the regular model, an S24+ and an S24 Ultra. All three are slated to run on Qualcomm’s Snapdragon 8 Gen 3.
The leak suggests Samsung will offer Space Zoom of up to 30x and dual telephoto zoom of up to 3x in the Galaxy S24 and S24+, while Ultra will probably have a beefier camera system. If the leak proves true, it will have a 200MP main lens, with up to 10x quad telephoto and 100x Space Zoom.
So far, the Samsung S24 lineup isn’t likely to have any terribly exciting upgrades in designs and pure specs. These are likely to include the company’s own Gauss generative AI systems, so as with Google’s Pixel series, the hardware may only tell half the tale. Let’s see what appears next year.
No high-speed transportation system between Europe and China.
David Becker via Getty Images
Hyperloop One had once dreamed of building a high-speed freight link between Europe and China, one that could take cargo from one end to the other in a single day. But the dream is pretty much dead. Hyperloop One is shutting down, a staff member has confirmed to Engadget after Bloomberg reported its closure. Which Hyperloop company was this again? From 2017 until 2022, it was known as Virgin Hyperloop One due to an investment from Richard Branson’s Virgin Group. Virgin quietly pulled its branding last year when the company abandoned its plans to transport passengers to focus on a cargo-only service. The company couldn’t secure a contract to build a working hyperloop system.
Beeper versus Apple has been our own little David and Goliath matchup, but it looks like the saga’s coming to a close. The Beeper Mini chat app, which lets Android users send iMessage missives to its iOS buddies, has issued yet another fix after Apple once again disabled access to the iMessage platform. The company says this will be the last fix released. Beeper wrote in a blog post today that it’s done “playing a cat-and-mouse game with the largest company” on the planet. Be warned: It’s… convoluted.
He hacked Rockstar Games from a hotel with a Fire TV stick.
Rockstar
A London judge has sentenced the teenage hacker who infiltrated Rockstar Games, leaking Grand Theft Auto VI footage, to an indefinite hospitalization. Arion Kurtaj breached Rockstar’s servers from a Travelodge hotel while under police custody, using only an Amazon Fire TV Stick, smartphone, keyboard and mouse. (He was promptly re-arrested.) Kurtaj was a central member of the Lasus$ international hacking group.
The two accomplices (the other is 17 so can’t be named) are the first Lapsus$ members to be convicted. Authorities believe others in the group (suspected to be primarily teenagers in the UK and Brazil) are still at large. It isn’t clear what kind of payoff the hackers got from the ransom requests, if any, as none of the affected companies have admitted to ponying up.
Microsoft is shutting down its Windows Mixed Reality platform, according to an official list of deprecated Windows features. This includes the garden variety Windows Mixed Reality software, along with the Mixed Reality Portal app and the affiliated Steam VR app. The platform isn’t gone yet, but Microsoft says it’ll be “removed in a future release of Windows.”
Microsoft first unveiled Windows Mixed Reality back in 2017 as its attempt to compete with rivals in the VR space, like HTC and Oculus (which is now owned by Meta.) We were fascinated by the tech when it launched as it offered the ability for in-person shared mixed reality. But uptake seemingly wasn’t big enough. Thank goodness I can still use MS Office on my Quest headset…
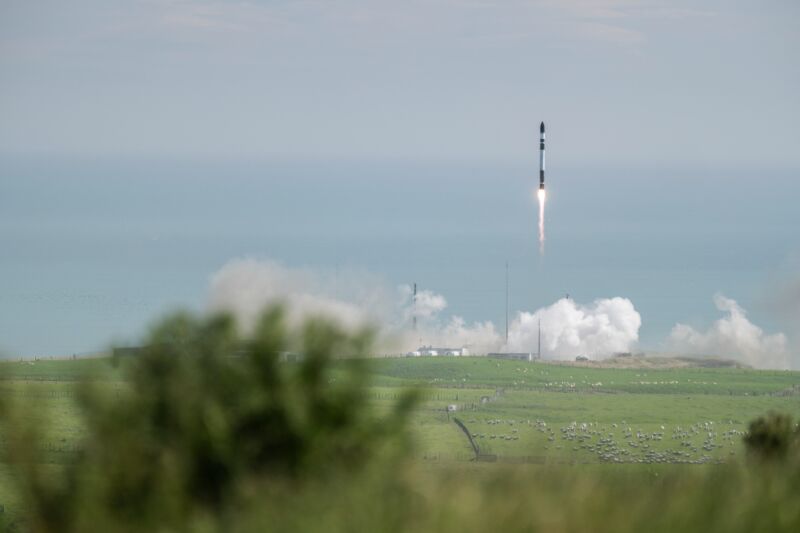
Enlarge/ Electron returned to flight successfully this week. (credit: Rocket Lab)
Welcome to Edition 6.24 of the Rocket Report! This will be the final edition of this newsletter until January 4—hey, space enthusiasts need a holiday break too! And given all that’s expected to happen in 2024 in the world of launch, a bit of a recharge seems like a smart move. Stephen and I wish everyone happy holidays and a healthy and prosperous new year. Until then!
As always, we welcome reader submissions, and if you don’t want to miss an issue, please subscribe using the box below (the form will not appear on AMP-enabled versions of the site). Each report will include information on small-, medium-, and heavy-lift rockets as well as a quick look ahead at the next three launches on the calendar.
Ranking the top 10 US launch companies of 2023. Oops, we did it again and published a list of the most accomplished US commercial launch companies. It’s no surprise that SpaceX is atop the list, but what comes after is more intriguing, including a new company in second position. I hope the list sparks debate, discussion, and appreciation for the challenge of operating a successful rocket company.
The latest Apple Watch’s big main draw was the double tap gesture control, but now the wearables maker is performing a more lethal kind of double tap on its latest Series 9 watches and premium Ultra 2 device. The company has already taken the device down from its online store, and in just two days, you’ll be cut off…