The week’s top three stories on the science beat all made me a little uncomfortable, to be honest. The news that scientists found a credible link between having a cat during your childhood and later being diagnosed with schizophrenia was troubling. Then there was the 2,400-year-old leather than turned out to be made…
First American, a real estate and mortgage financial firm, experienced a “cybersecurity incident” impacting operations, the company posted on its website on Thursday. The company has not released any details about what happened, but as of the time of publication, its website remained down.
“First American has experienced a cybersecurity incident,” says a statement on its website. “In response, we have taken certain systems offline and are working to return to normal business operations as soon as possible.” First American did not immediately respond to a request for comment.
In 2019, First American came under fire for its handling of sensitive information. It paid a $1 million fine to the New York State Department of Financial Services after a vulnerability in its proprietary “EaglePro” application left data like social security numbers and bank information exposed.
This article originally appeared on Engadget at https://www.engadget.com/first-american-discloses-a-cybersecurity-incident-a-few-years-after-its-major-leak-145141277.html?src=rss
India is testing AI to build climate models to improve weather forecasting as torrential rains, floods and droughts proliferate across the vast country, a top weather official said. From a report: Global warming has triggered more intense clashes of weather systems in India in recent years, increasing extreme weather events, which the independent Centre for Science and Environment estimates have killed nearly 3,000 people this year. Weather agencies around the world are focussing on AI, which can bring down cost and improve speed, and which Britain’s Met Office says could “revolutionise” weather forecasting, with a recent Google-funded model found to have outperformed conventional methods.
Accurate weather forecasting is particularly crucial in India, a country of 1.4 billion people, many impoverished, and the world’s second-largest producer of rice, wheat and sugar. The India Meteorological Department (IMD) provides forecasts based on mathematical models using supercomputers. Using AI with an expanded observation network could help generate higher-quality forecast data at lower cost. The department expects the AI-based climate models and advisories it is developing to help improve forecasts, K.S. Hosalikar, head of climate research and services at IMD, told Reuters.
If you haven’t heard, the popular budgeting app Mint is about to go away. Parent company Intuit will shut down the service on March 24, 2024. The company suggests folks migrate to its other personal finance app, Credit Karma. Mint had 3.6 million active users as of 2021, according to Bloomberg, and I’m one of them. I use the app to track all of my accounts in one place without having to log into too many disparate banking apps. But I’ve also used it to monitor my credit score, stick to a monthly budget, and set goals like building a rainy-day fund or paying down my mortgage faster.
Intuit has not commented on whether it intends to fold Mint’s budgeting features into Credit Karma but as it stands, Credit Karma is not a Mint substitute: It’s meant to monitor your credit and, Intuit hopes, steer you toward credit cards and various other financial products.
So, over the past month, I’ve downloaded a good half-dozen competing money apps to see if any might cut it as a permanent Mint replacement. What follows is the guide I would have wanted to read: a comparison of budgeting apps that promise to track your net worth and spending in one place. Join me as I fall down a rabbit hole.
How we tested
First, I had to do some research. To find a list of apps to test, I consulted trusty ol’ Google (and even trustier Reddit); read reviews of popular apps on the App Store; and also asked friends and colleagues what budget tracking apps they might be using. Some of the apps I found were free, just like Mint. These, of course, show loads of ads (excuse me, “offers”) to stay in business. But most of the available apps require paid subscriptions, with prices typically topping out around $100 a year, or $15 a month. (Spoiler: My top pick is cheaper than that.)
Since this guide is meant to help Mint users find a permanent replacement, any services I chose to test needed to do several things: import all of your account data into one place; offer budgeting tools; and track your spending, net worth and credit score. Except where noted, all of these apps are available for iOS, Android and on the web.
Once I had my shortlist of six apps, I got to work setting them up. For the sake of thoroughly testing these apps (and remember, I really was looking for a Mint alternative myself), I made a point of adding every account to every tracking app, no matter how small or immaterial the balance. What ensued was a veritable Groundhog Day of two-factor authentication. Just hours of entering passwords and one-time passcodes, for the same banks half a dozen times over. Hopefully, you only have to do this once.
What is Plaid and how does it work?
Dana Wollman / Engadget
Each of the apps I tested uses the same underlying network, called Plaid, to pull in financial data, so it’s worth explaining up top what it is and how it works. Plaid was founded as a fintech startup in 2013 and is today the industry standard in connecting banks with third-party apps. Plaid works with over 12,000 financial institutions across the US, Canada and Europe. Additionally, more than 8,000 third-party apps and services rely on Plaid, the company claims.
To be clear, you don’t need a dedicated Plaid app to use it; the technology is baked into a wide array of apps, including the budget trackers I tested for this guide. Once you find the “add an account” option in whichever one you’re using, you’ll see a menu of commonly used banks. There’s also a search field you can use to look yours up directly. Once you find yours, you’ll be prompted to enter your login credentials. If you have two-factor authentication set up, you’ll need to enter a one-time passcode as well.
As the middleman, Plaid is a passthrough for information that may include your account balances, transaction history, account type and routing or account number. Plaid uses encryption, and says it has a policy of not selling or renting customer data to other companies. However, I would not be doing my job if I didn’t note that in 2022 Plaid was forced to pay $58 million to consumers in a class action suit for collecting “more financial data than was needed.” As part of the settlement, Plaid was compelled to change some of its business practices.
In a statement provided to Engadget, a Plaid spokesperson said the company continues to deny the allegations underpinning the lawsuit and that “the crux of the non-financial terms in the settlement are focused on us accelerating workstreams already underway related to giving people more transparency into Plaid’s role in connecting their accounts, and ensuring that our workstreams around data minimization remain on track.”
How to import your financial data from Mint
If only importing data from Mint were as easy as entering your credentials from inside your new budgeting app and hitting “import.” In fact, any app that advertises the ability to port over your stats from Mint is just going to have you upload a CSV file of transactions and other data.
To download a CSV file from Mint, do the following:
Sign into Mint.com and hit Transactions in the menu on the left side of the screen.
Select an account, or all accounts.
Scroll down and look for “export [number] transactions” in smaller print.
Your CSV file should begin downloading.
Note: Downloading on a per-account basis might seem more annoying, but could help you get set up on the other side, if the app you’re using has you importing transactions one-for-one into their corresponding accounts.
The best budgeting app overall: Quicken Simplifi
No pun intended, but what I like about Quicken Simplifi is its simplicity. Whereas other apps try to distinguish themselves with dark themes and customizable emoji, Simplifi has a clean user interface, with a landing page that you just keep scrolling through to get a detailed overview of all your stats. These include your top-line balances; net worth; recent spending; upcoming recurring payments; a snapshot of your spending plan; top spending categories; achievements; and any watchlists you’ve set up. You can also set up savings goals elsewhere in the app. I also appreciate how it offers neat, almost playful visualizations without ever looking cluttered. I felt at home in the mobile and web dashboards after a day or so, which is faster than I adapted to some competing services (I’m looking at you, YNAB and Monarch).
Getting set up with Simplifi was mostly painless. I was particularly impressed at how easily it connected to Fidelity; not all budget trackers do, for whatever reason. This is also one of the only services I tested that gives you the option of inviting a spouse or financial advisor to co-manage your account.
Dana Wollman / Engadget
In practice, Simplifi miscategorized some of my expenses, but nothing out of the ordinary compared to any of these budget trackers. As you’re reviewing transactions, you can also mark if you’re expecting a refund, which is a unique feature among the services I tested. Simplifi also estimated my regular income better than some other apps I tested. Most of all, I appreciated the option of being able to categorize some, but not all, purchases from a merchant as recurring. For instance, I can add my two Amazon subscribe-and-saves as recurring payments, without having to create a broad-strokes rule for every Amazon purchase.
The budgeting feature is also self-explanatory. Just check that your regular income is accurate and be sure to set up recurring payments, making note of which are bills and which are subscriptions. This is important because Simplifi shows you your total take-home income as well as an “income after bills” figure. That number includes, well, bills but not discretionary subscriptions. From there, you can add spending targets by category in the “planned spending” bucket. Planned spending can also include one-time expenditures, not just monthly budgets. When you create a budget, Simplifi will suggest a number based on a six-month average.
Not dealbreakers, but two things to keep in mind as you get started: Simplifi is notable in that you can’t set up an account through Apple or Google. There is also no option for a free trial, though Quicken promises a “30-day money back guarantee.”
The best budgeting app (runner-up): Monarch Money
Monarch Money grew on me. My first impression of the app, which was founded by a former Mint product manager, was that it’s more difficult to use than others on this list, including Simplifi, NerdWallet and Copilot. And it is. Editing expense categories, adding recurring transactions and creating rules, for example, is a little more complicated than it needs to be, especially in the mobile app. (My advice: Use the web app for fine-tuning details.) Monarch also didn’t get my income right; I had to edit it.
Once you’re set up, though, Monarch offers an impressive level of granularity. In the budgets section, you can see a bona fide balance sheet showing budgets and actuals for each category. You’ll also find a forecast, for the year or by month. And recurring expenses can be set not just by merchant, but other parameters as well. For instance, while most Amazon purchases might be marked as “shopping,” those for the amounts of $54.18 or $34.18 are definitely baby supplies, and can be automatically marked as such each time, not to mention programmed as recurring payments. Weirdly, though, there’s no way to mark certain recurring payments as bills, specifically.
Dana Wollman / Engadget
The mobile app is mostly self-explanatory. The main dashboard shows your net worth; your four most recent transactions; a month-over-month spending comparison; income month-to-date; upcoming bills; an investments snapshot; a list of any goals you’ve set; and, finally, a link to your month-in-review. That month-in-review is more detailed than most, delving into cash flow; top income and expense categories; cash flow trends; changes to your net worth, assets and liabilities; plus asset and liability breakdowns.
On the main screen, you’ll also find tabs for accounts, transactions, cash flow, budget and recurring. Like many of the other apps featured here, Monarch can auto-detect recurring expenses and income, even if it gets the category wrong. (They all do to an extent.) Expense categories are marked by emoji, which you can customize if you’re so inclined.
Monarch Money uses a combination of Plaid and Finicity, a competing network owned by Mastercard. Similar to NerdWallet, I found myself completing two-factor authentication every time I wanted to get past the Plaid screen to add another account. Notably, Monarch is the only other app I tested that allows you to grant access to someone else in your family — likely a spouse or financial advisor. Monarch also has a Chrome extension for importing from Mint, though really this is just a shortcut for downloading a CSV file, which you’ll have to do regardless of where you choose to take your Mint data.
The best up-and-comer: Copilot Money
Copilot Money might be the best-looking budget tracker I tested. It also has the distinction of being exclusive to iOS and Macs — at least for now. Andres Ugarte, the company’s CEO, has publicly promised that Android and web apps are coming in 2024 (more likely the second half of the year, Ugarte tells me). But until it follows through, I can’t recommend Copilot for most people with so many good competitors out there.
Copilot Money for Web and Android!
Thanks to the support from our users, and the overwhelming positive reception we’re seeing from folks migrating from Mint, we can now say that we’ll be building @copilotmoney for Web and Android with a goal to launch in 2024.
There are other features that Copilot is missing, which I’ll get into. But it is promising, and one to keep an eye on. It’s just a fast, efficient, well designed app, and Android users will be in for a treat when they’ll finally be able to download it. It makes good use of colors, emoji and graphs to help you understand at a glance how you’re doing on everything from your budgets to your investment performance to your credit card debt over time. In particular, Copilot does a better job than almost any other app of visualizing your recurring monthly expenses.
Behind those punchy colors and cutesy emoji, though, is some sophisticated performance. Copilot’s AI-powered “Intelligence” gets smarter as you go at categorizing your expenses. (You can also add your own categories, complete with your choice of emoji.) It’s not perfect. Copilot miscategorized some purchases (they all do), but it makes it easier to edit than most. On top of that, the internal search feature is very fast; it starts whittling down results in your transaction history as soon as you begin typing.
Dana Wollman / Engadget
Copilot is also unique in offering Amazon and Venmo integrations, allowing you to see transaction details. With Amazon, this requires just signing into your Amazon account via an in-app browser. For Venmo, you have to set up fwd@copilot.money as a forwarding address and then create a filter, wherein emails from venmo@venmo.com are automatically forwarded to fwd@copilot.money.
While the app is heavily automated, I still appreciate that Copilot marks new transactions for review. It’s a good way to both weed out fraudulent charges, and also be somewhat intentional about your spending habits.
Because the app is relatively new (it launched in early 2020), the company is still catching up to the competition on some table-stakes features. Ugarte told me that his team is almost done building out a detailed cash flow section, which could launch before the end of 2023, but more likely in early 2024. On its website, Copilot also promises a raft of AI-powered features that build on its current “Intelligence” platform, the one that powers its smart expense categorization. These include “smart financial goals,” natural language search, a chat interface, forecasting and benchmarking. That benchmarking, Ugarte tells me, is meant to give people a sense of how they’re doing compared to other Copilot users, on both spending and investment performance. Most of these features should arrive in the new year.
Copilot does a couple interesting things for new customers that distinguish it from the competition. There’s a “demo mode” that feels like a game simulator; no need to add your own accounts. The company is also offering two free months with RIPMINT — a more generous introductory offer than most. When it finally does come time to pony up, the $7.92 monthly plan is cheaper than some competing apps, although the $95-a-year-option is in the same ballpark.
The best free budgeting app: NerdWallet
You may know NerdWallet as a site that offers a mix of personal finance news, explainers and guides. I see it often when I google a financial term I don’t know and sure enough, it’s one of the sites I’m most likely to click on. As it happens, NerdWallet also has the distinction of offering one of the only free budget tracking apps I tested. In fact, there is no paid version; nothing is locked behind a paywall. The main catch: There are ads everywhere. To be fair, the free version of Mint was like this, too.
Even with the inescapable credit card offers, NerdWallet has a clean, easy-to-understand user interface, which includes both a web and a mobile app. The key metrics that it highlights most prominently are your cash flow, net worth and credit score. (Of note, although Mint itself offered credit score monitoring, most of its rivals do not.) I particularly enjoyed the weekly insights, which delve into things like where you spent the most money or how much you paid in fees — and how that compares to the previous month. Because this is NerdWallet, an encyclopedia of financial info, you get some particularly specific category options when setting up your accounts (think: a Roth or non-Roth IRA).
Dana Wollman / Engadget
As a budgeting app, NerdWallet is more than serviceable, if a bit basic. Like other apps I tested, you can set up recurring bills. Importantly, it follows the popular 50/30/20 budgeting rule, which has you putting 50% of your budget toward things you need, 30% toward things you want, and the remaining 20% into savings or debt repayments. If this works for you, great — just know that you can’t customize your budget to the same degree as some competing apps. You can’t currently create custom spending categories, though a note inside the dashboard section of the app says “you’ll be able to customize them in the future.” You also can’t move items from the wants column to “needs” or vice versa but “In the future, you’ll be able to move specific transactions to actively manage what falls into each group.” A NerdWallet spokesperson declined to provide an ETA, though.
Lastly, it’s worth noting that NerdWallet had one of the most onerous setup processes of any app I tested. I don’t think this is a dealbreaker, as you’ll only have to do it once and, hopefully, you aren’t setting up six or seven apps in tandem as I was. What made NerdWallet’s onboarding especially tedious is that every time I wanted to add an account, I had to go through a two-factor authentication process to even get past the Plaid splash screen, and that’s not including the 2FA I had set up at each of my banks. This is a security policy on NerdWallet’s end, not Plaid’s, a Plaid spokesperson says.
Precisely because NerdWallet is one of the only budget trackers to offer credit score monitoring, it also needs more of your personal info during setup, including your birthday, address, phone number and the last four digits of your social security number. It’s the same with Credit Karma, which also does credit score monitoring.
Related to the setup process, I found that NerdWallet was less adept than other apps at automatically detecting my regular income. In my case, it counted a large one-time wire transfer as income, at which point my only other option was to enter my income manually (which is slightly annoying because I would have needed my pay stub handy to double-check my take-home pay).
Budgeting apps we also tested
YNAB
YNAB is, by its own admission, “different from anything you’ve tried before.” The app, whose name is short for You Need a Budget, promotes a so-called zero-based budgeting system, which forces you to assign a purpose for every dollar you earn. A frequently used analogy is to put each dollar in an envelope; you can always move money from one envelope to another in a pinch. These envelopes can include rent and utilities, along with unforeseen expenses like holiday gifts and the inevitable car repair. The idea is that if you budget a certain amount for the unknowns each month, they won’t feel like they’re sneaking up on you.
Importantly, YNAB is only concerned with the money you have in your accounts now. The app does not ask you to provide your take-home income or set up recurring income payments (although there is a way to do this). The money you will make later in the month through your salaried job is not relevant, because YNAB does not engage in forecasting.
The app is harder to learn than any other here, and it requires more ongoing effort from the user. And YNAB knows that. Inside both the mobile and web apps are links to videos and other tutorials. Although I never quite got comfortable with the user interface, I did come to appreciate YNAB’s insistence on intentionality. Forcing users to draft a new budget each month and to review each transaction is not necessarily a bad thing. As YNAB says on its website, “Sure, you’ve got pie charts showing that you spent an obscene amount of money in restaurants — but you’ve still spent an obscene amount of money in restaurants.” I can see this approach being useful for people who don’t tend to have a lot of cash in reserve at a given time, or who have spending habits they want to correct (to riff off of YNAB’s own example, ordering Seamless four times a week).
My colleague Valentina Palladino, knowing I was working on this guide, penned a respectful rebuttal, explaining why she’s been using YNAB for years. Perhaps, like her, you have major savings goals you want to achieve, whether it’s paying for a wedding or buying a house. I suggest you give her column a read. For me, though, YNAB’s approach feels like overkill.
PocketGuard
PocketGuard is one of the only reputable free budget trackers I found in my research. Just know it’s far more restricted at the free tier than NerdWallet or Mint. In my testing, I was prompted to pay after I attempted to link more than two bank accounts. So much for free, unless you keep things simple with one cash account and one credit card. When it comes time to upgrade to PocketGuard Plus, you have three options: pay $7.99 a month, $34.99 a year or $79.99 for a one-time lifetime license. That lifetime option is actually one of the few unique selling points for me: I’m sure some people will appreciate paying once and never having to, uh, budget for it again.
From the main screen, you’ll see tabs for accounts, insights, transactions and the “Plan,” which is where you see recurring payments stacked on top of what looks like a budget. The main overview screen shows you your net worth, total assets and debts; net income and total spending for the month; upcoming bills; a handy reminder of when your next paycheck lands; any debt payoff plan you have; and any goals.
Dana Wollman / Engadget
Like some other apps, including Quicken Simplifi, PocketGuard promotes an “after bills” approach, where you enter all of your recurring bills, and then PocketGuard shows you what’s left, and that’s what you’re supposed to be budgeting: your disposable income. Obviously, other apps have a different philosophy: take into account all of your post-tax income and use it to pay the bills, purchase things you want and maybe even save a little. But in PocketGuard, it’s the “in your pocket” number that’s most prominent. To PocketGuard’s credit, it does a good job visualizing which bills are upcoming and which ones you’ve already paid.
PocketGuard has also publicly committed to adding some popular features in early 2024. These include rollover budgeting in January 2024, categorization rules in February and shared household access in March.
Dana Wollman / Engadget
Although PocketGuard’s UI is easy enough to understand, it lacks polish. The “accounts” tab is a little busy, and doesn’t show totals for categories like cash or investments. Seemingly small details like weirdly phrased or punctuated copy occasionally make the app feel janky. More than once, it prompted me to update the app when no updates were available. The web version, meanwhile, feels like the mobile app blown up to a larger format and doesn’t take advantage of the extra screen real estate.
Of note, although PocketGuard does work with Plaid, its primary bank-connecting platform is actually Finicity. Setting up my accounts through Finicity was mostly a straightforward process. I did encounter one hiccup: Finicity would not connect to my SoFi account. I was able to do it through Plaid, but PocketGuard doesn’t make it easy to access Plaid in the app. The only way, as far as I can tell, is to knowingly search for the name of a bank that isn’t available through Finicity, at which point you get the option to try Plaid instead. Like I said: the experience can be janky.
This article originally appeared on Engadget at https://www.engadget.com/the-best-budgeting-apps-to-replace-mint-143047346.html?src=rss
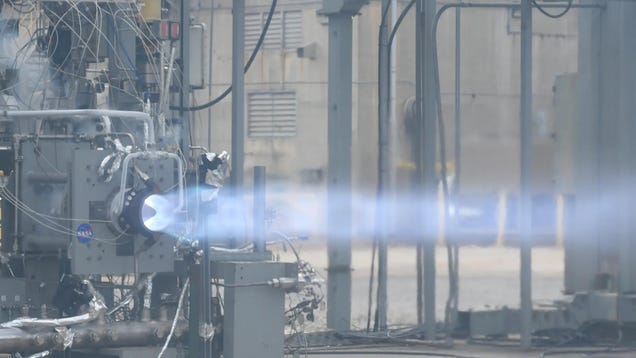
NASA just put its new propulsion system to the test, powering a 3D-printed rotating detonation rocket engine for a sustained burn that lasted three times as long as the first test.
Last year, I mused over whether foldable smartphones would ever be affordable. I wanted to see them take off after falling in love with the Galaxy Z Fold 4. This year, I got my answer. It’s a resounding “No,” especially with the foldable market as it is right now. Even with the recently launched Motorola Razr, a flip…
PlayStation will no longer be removing over 1,300 Discovery TV shows from its platform next month. From a report: Sony had previously announced that users will not be able to watch Discovery content on PlayStation from December 31, even if they had already purchased it. However, the firm now says that due to an ‘updated licensing agreement’ with Warner Bros — which owns the Discovery brand — consumers will now be able to access their previously purchased shows ‘for at least the next 30 months.’
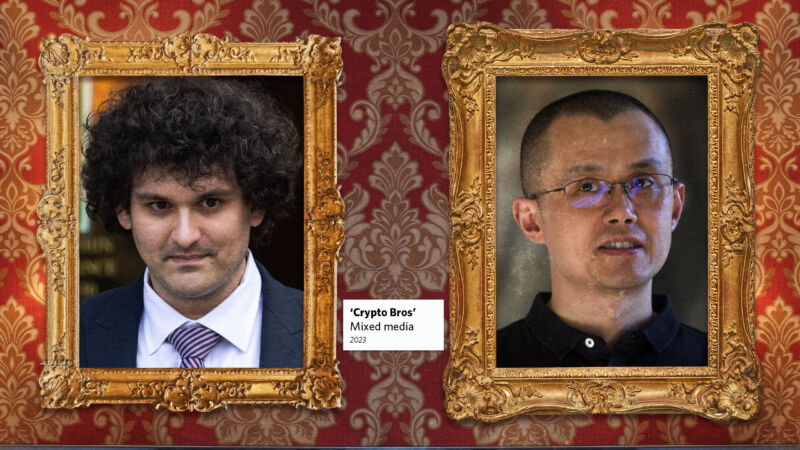
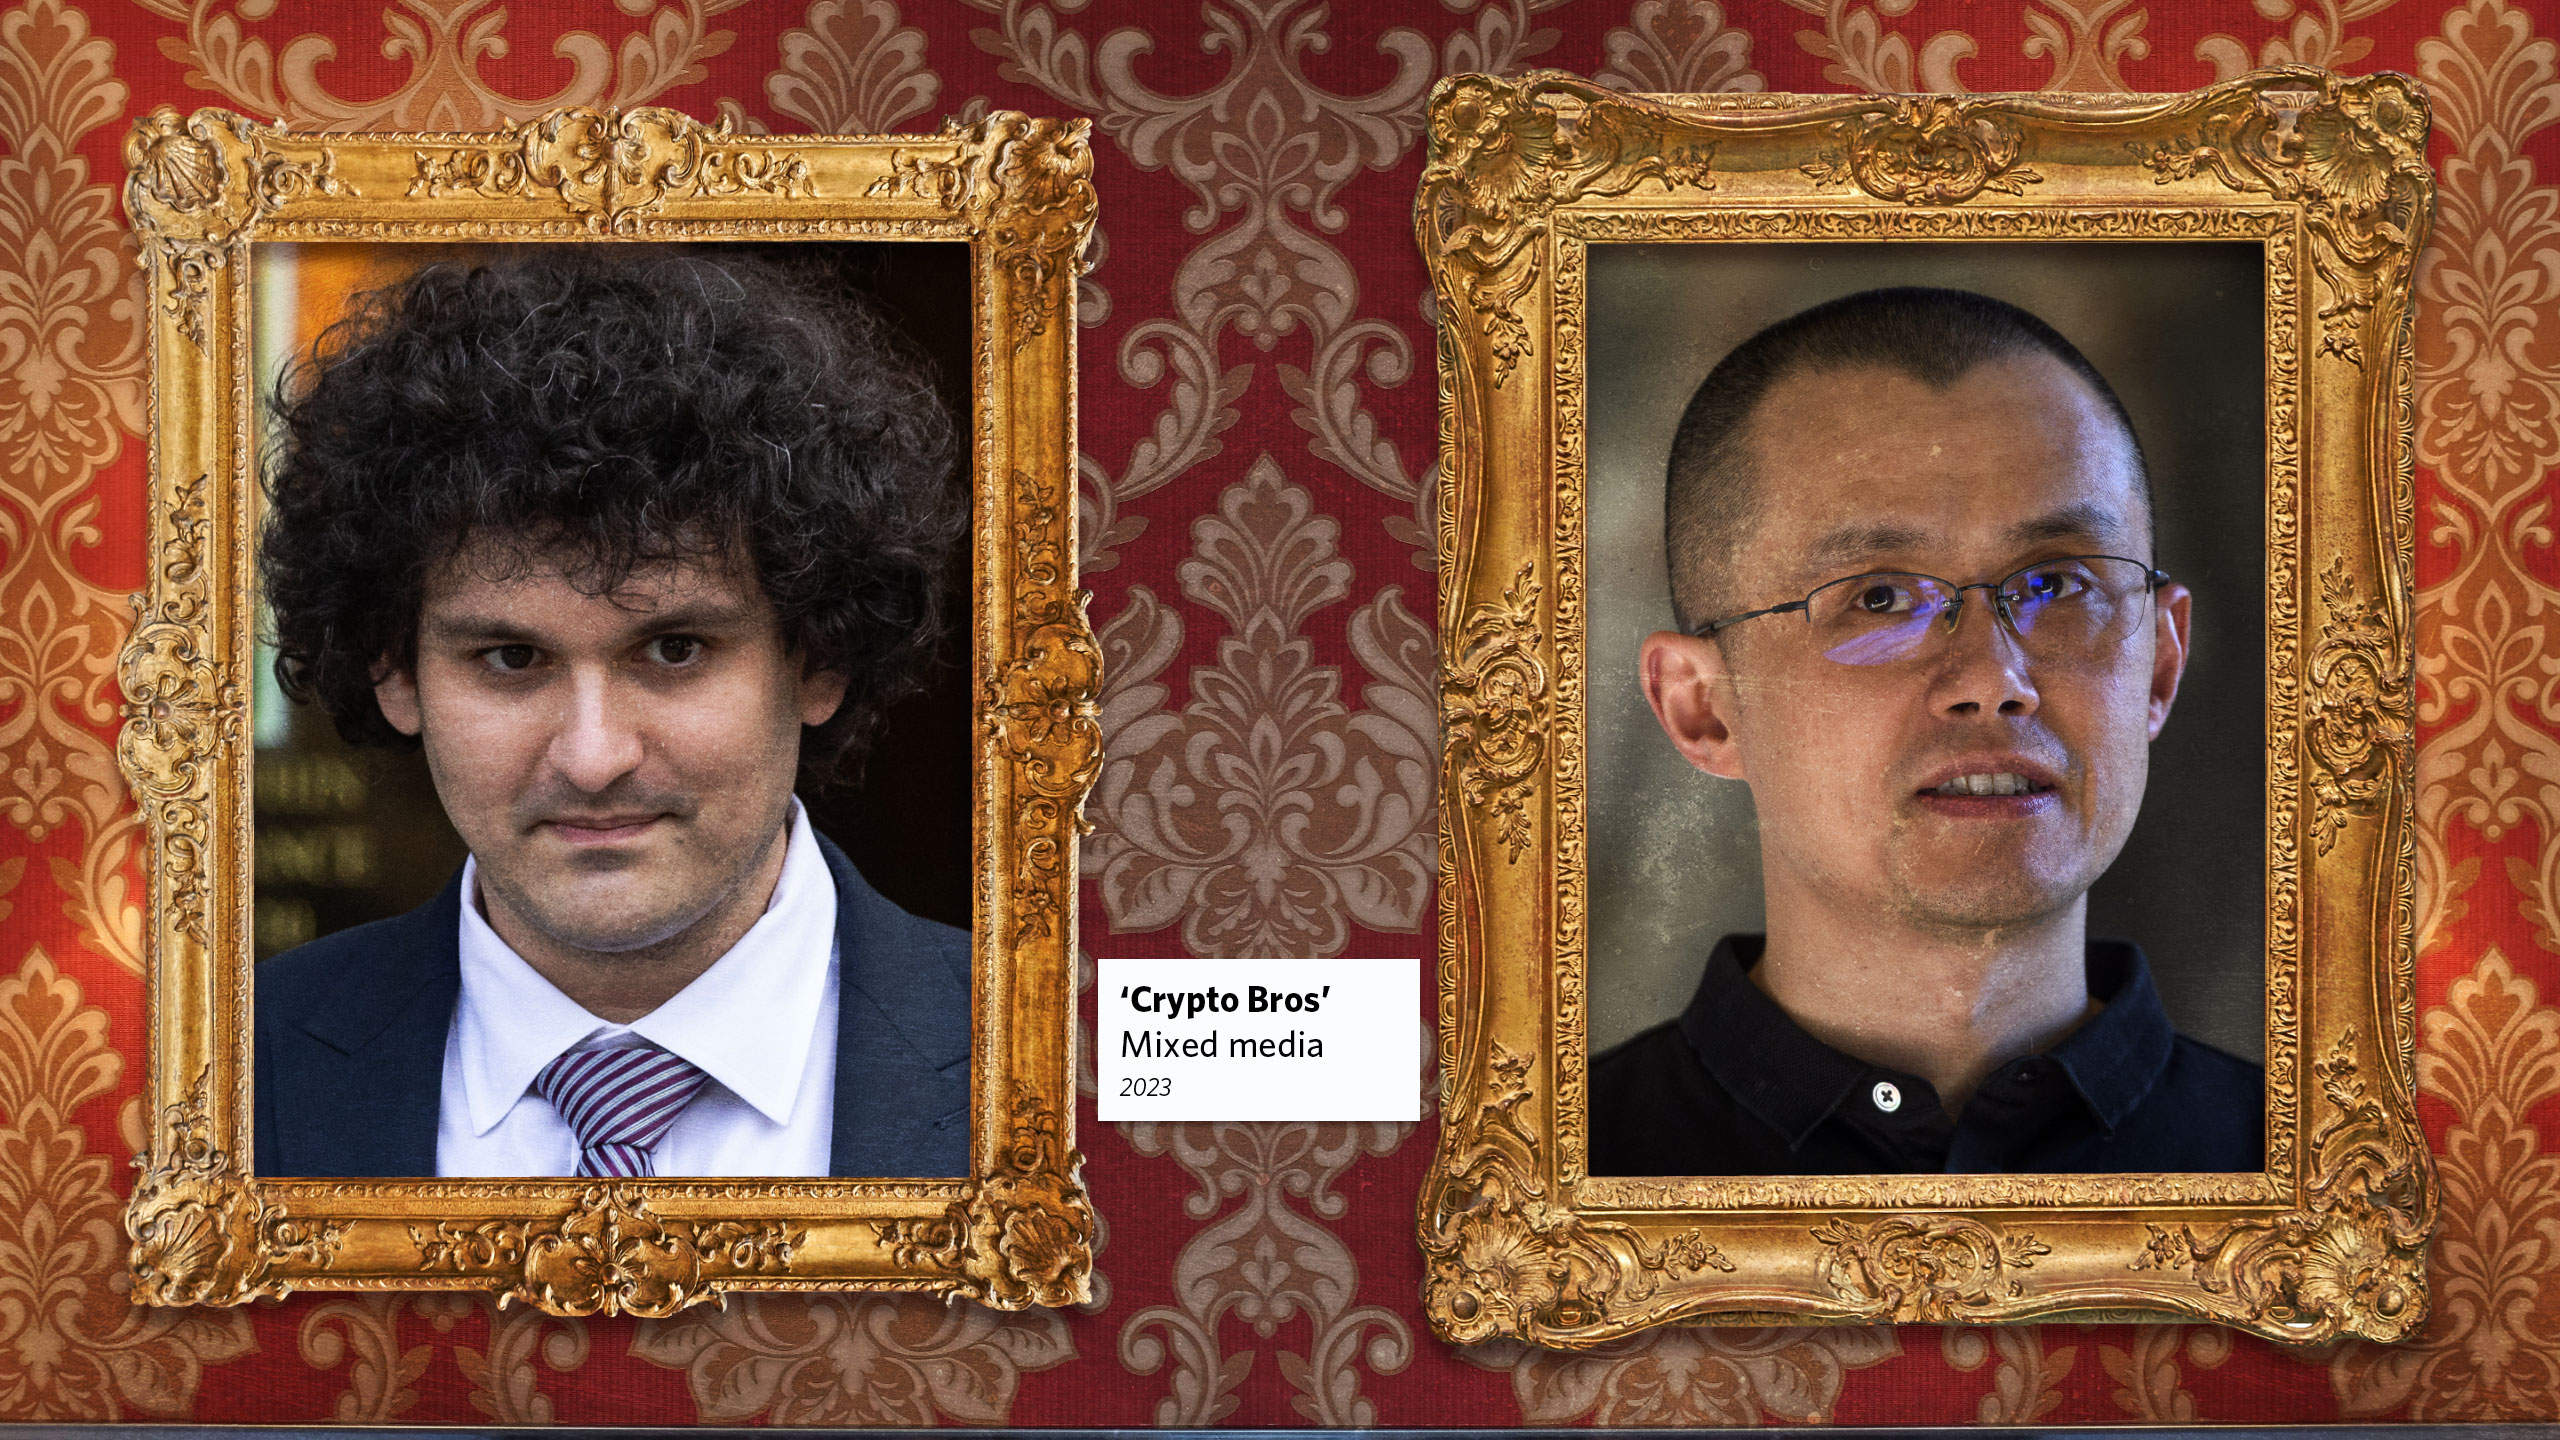
Looking back, 2023 will likely be remembered as the year of the fallen crypto bro.
While celebrities like Kim Kardashian and Matt Damon last year faced public backlash after shilling for cryptocurrency, this year’s top headlines traced the downfalls of two of the most successful and influential crypto bros of all time: FTX co-founder Sam Bankman-Fried (often referred to as SBF) and Binance founder Changpeng Zhao (commonly known as CZ).
At 28 years old, Bankman-Fried made Forbes’ 30 Under 30 list in 2021, but within two short years, his recently updated Forbes profile notes that the man who was once “one of the richest people in crypto” in “a stunning fall from grace” now has a real-time net worth of $0.
When you drop money in the bank, it looks like it’s just sitting there, ready for you to withdraw. In reality, your institution makes money on your money by lending it elsewhere, including to the fossil fuel companies driving climate change, as well as emissions-heavy industries like manufacturing.
So just by leaving money in a bank account, you’re unwittingly contributing to worsening catastrophes around the world. According to a new analysis, for every $1,000 dollars the average American keeps in savings, each year they indirectly create emissions equivalent to flying from New York to Seattle. “We don’t really take a look at how the banks are using the money we keep in our checking account on a daily basis, where that money is really circulating,” says Jonathan Foley, executive director of Project Drawdown, which published the analysis. “But when we look under the hood, we see that there’s a lot of fossil fuels.”
Generative artificial intelligence is everywhere you look these days, including on the web: advanced predictive text bots such as ChatGPT can now spew out endless reams of text on every topic imaginable and make all this written content natural enough that it could plausibly have been written by a human being.
Along with a countdown showing the next Unpacked will be on January 17, leaker Evan Blass shared a spec sheet that purports to break down the components of the Galaxy S24 lineup. Just like the S23 (pictured above), expect three Galaxy devices: the regular model, an S24+ and an S24 Ultra. All three are slated to run on Qualcomm’s Snapdragon 8 Gen 3.
The leak suggests Samsung will offer Space Zoom of up to 30x and dual telephoto zoom of up to 3x in the Galaxy S24 and S24+, while Ultra will probably have a beefier camera system. If the leak proves true, it will have a 200MP main lens, with up to 10x quad telephoto and 100x Space Zoom.
So far, the Samsung S24 lineup isn’t likely to have any terribly exciting upgrades in designs and pure specs. These are likely to include the company’s own Gauss generative AI systems, so as with Google’s Pixel series, the hardware may only tell half the tale. Let’s see what appears next year.
No high-speed transportation system between Europe and China.
David Becker via Getty Images
Hyperloop One had once dreamed of building a high-speed freight link between Europe and China, one that could take cargo from one end to the other in a single day. But the dream is pretty much dead. Hyperloop One is shutting down, a staff member has confirmed to Engadget after Bloomberg reported its closure. Which Hyperloop company was this again? From 2017 until 2022, it was known as Virgin Hyperloop One due to an investment from Richard Branson’s Virgin Group. Virgin quietly pulled its branding last year when the company abandoned its plans to transport passengers to focus on a cargo-only service. The company couldn’t secure a contract to build a working hyperloop system.
Beeper versus Apple has been our own little David and Goliath matchup, but it looks like the saga’s coming to a close. The Beeper Mini chat app, which lets Android users send iMessage missives to its iOS buddies, has issued yet another fix after Apple once again disabled access to the iMessage platform. The company says this will be the last fix released. Beeper wrote in a blog post today that it’s done “playing a cat-and-mouse game with the largest company” on the planet. Be warned: It’s… convoluted.
He hacked Rockstar Games from a hotel with a Fire TV stick.
Rockstar
A London judge has sentenced the teenage hacker who infiltrated Rockstar Games, leaking Grand Theft Auto VI footage, to an indefinite hospitalization. Arion Kurtaj breached Rockstar’s servers from a Travelodge hotel while under police custody, using only an Amazon Fire TV Stick, smartphone, keyboard and mouse. (He was promptly re-arrested.) Kurtaj was a central member of the Lasus$ international hacking group.
The two accomplices (the other is 17 so can’t be named) are the first Lapsus$ members to be convicted. Authorities believe others in the group (suspected to be primarily teenagers in the UK and Brazil) are still at large. It isn’t clear what kind of payoff the hackers got from the ransom requests, if any, as none of the affected companies have admitted to ponying up.
Microsoft is shutting down its Windows Mixed Reality platform, according to an official list of deprecated Windows features. This includes the garden variety Windows Mixed Reality software, along with the Mixed Reality Portal app and the affiliated Steam VR app. The platform isn’t gone yet, but Microsoft says it’ll be “removed in a future release of Windows.”
Microsoft first unveiled Windows Mixed Reality back in 2017 as its attempt to compete with rivals in the VR space, like HTC and Oculus (which is now owned by Meta.) We were fascinated by the tech when it launched as it offered the ability for in-person shared mixed reality. But uptake seemingly wasn’t big enough. Thank goodness I can still use MS Office on my Quest headset…
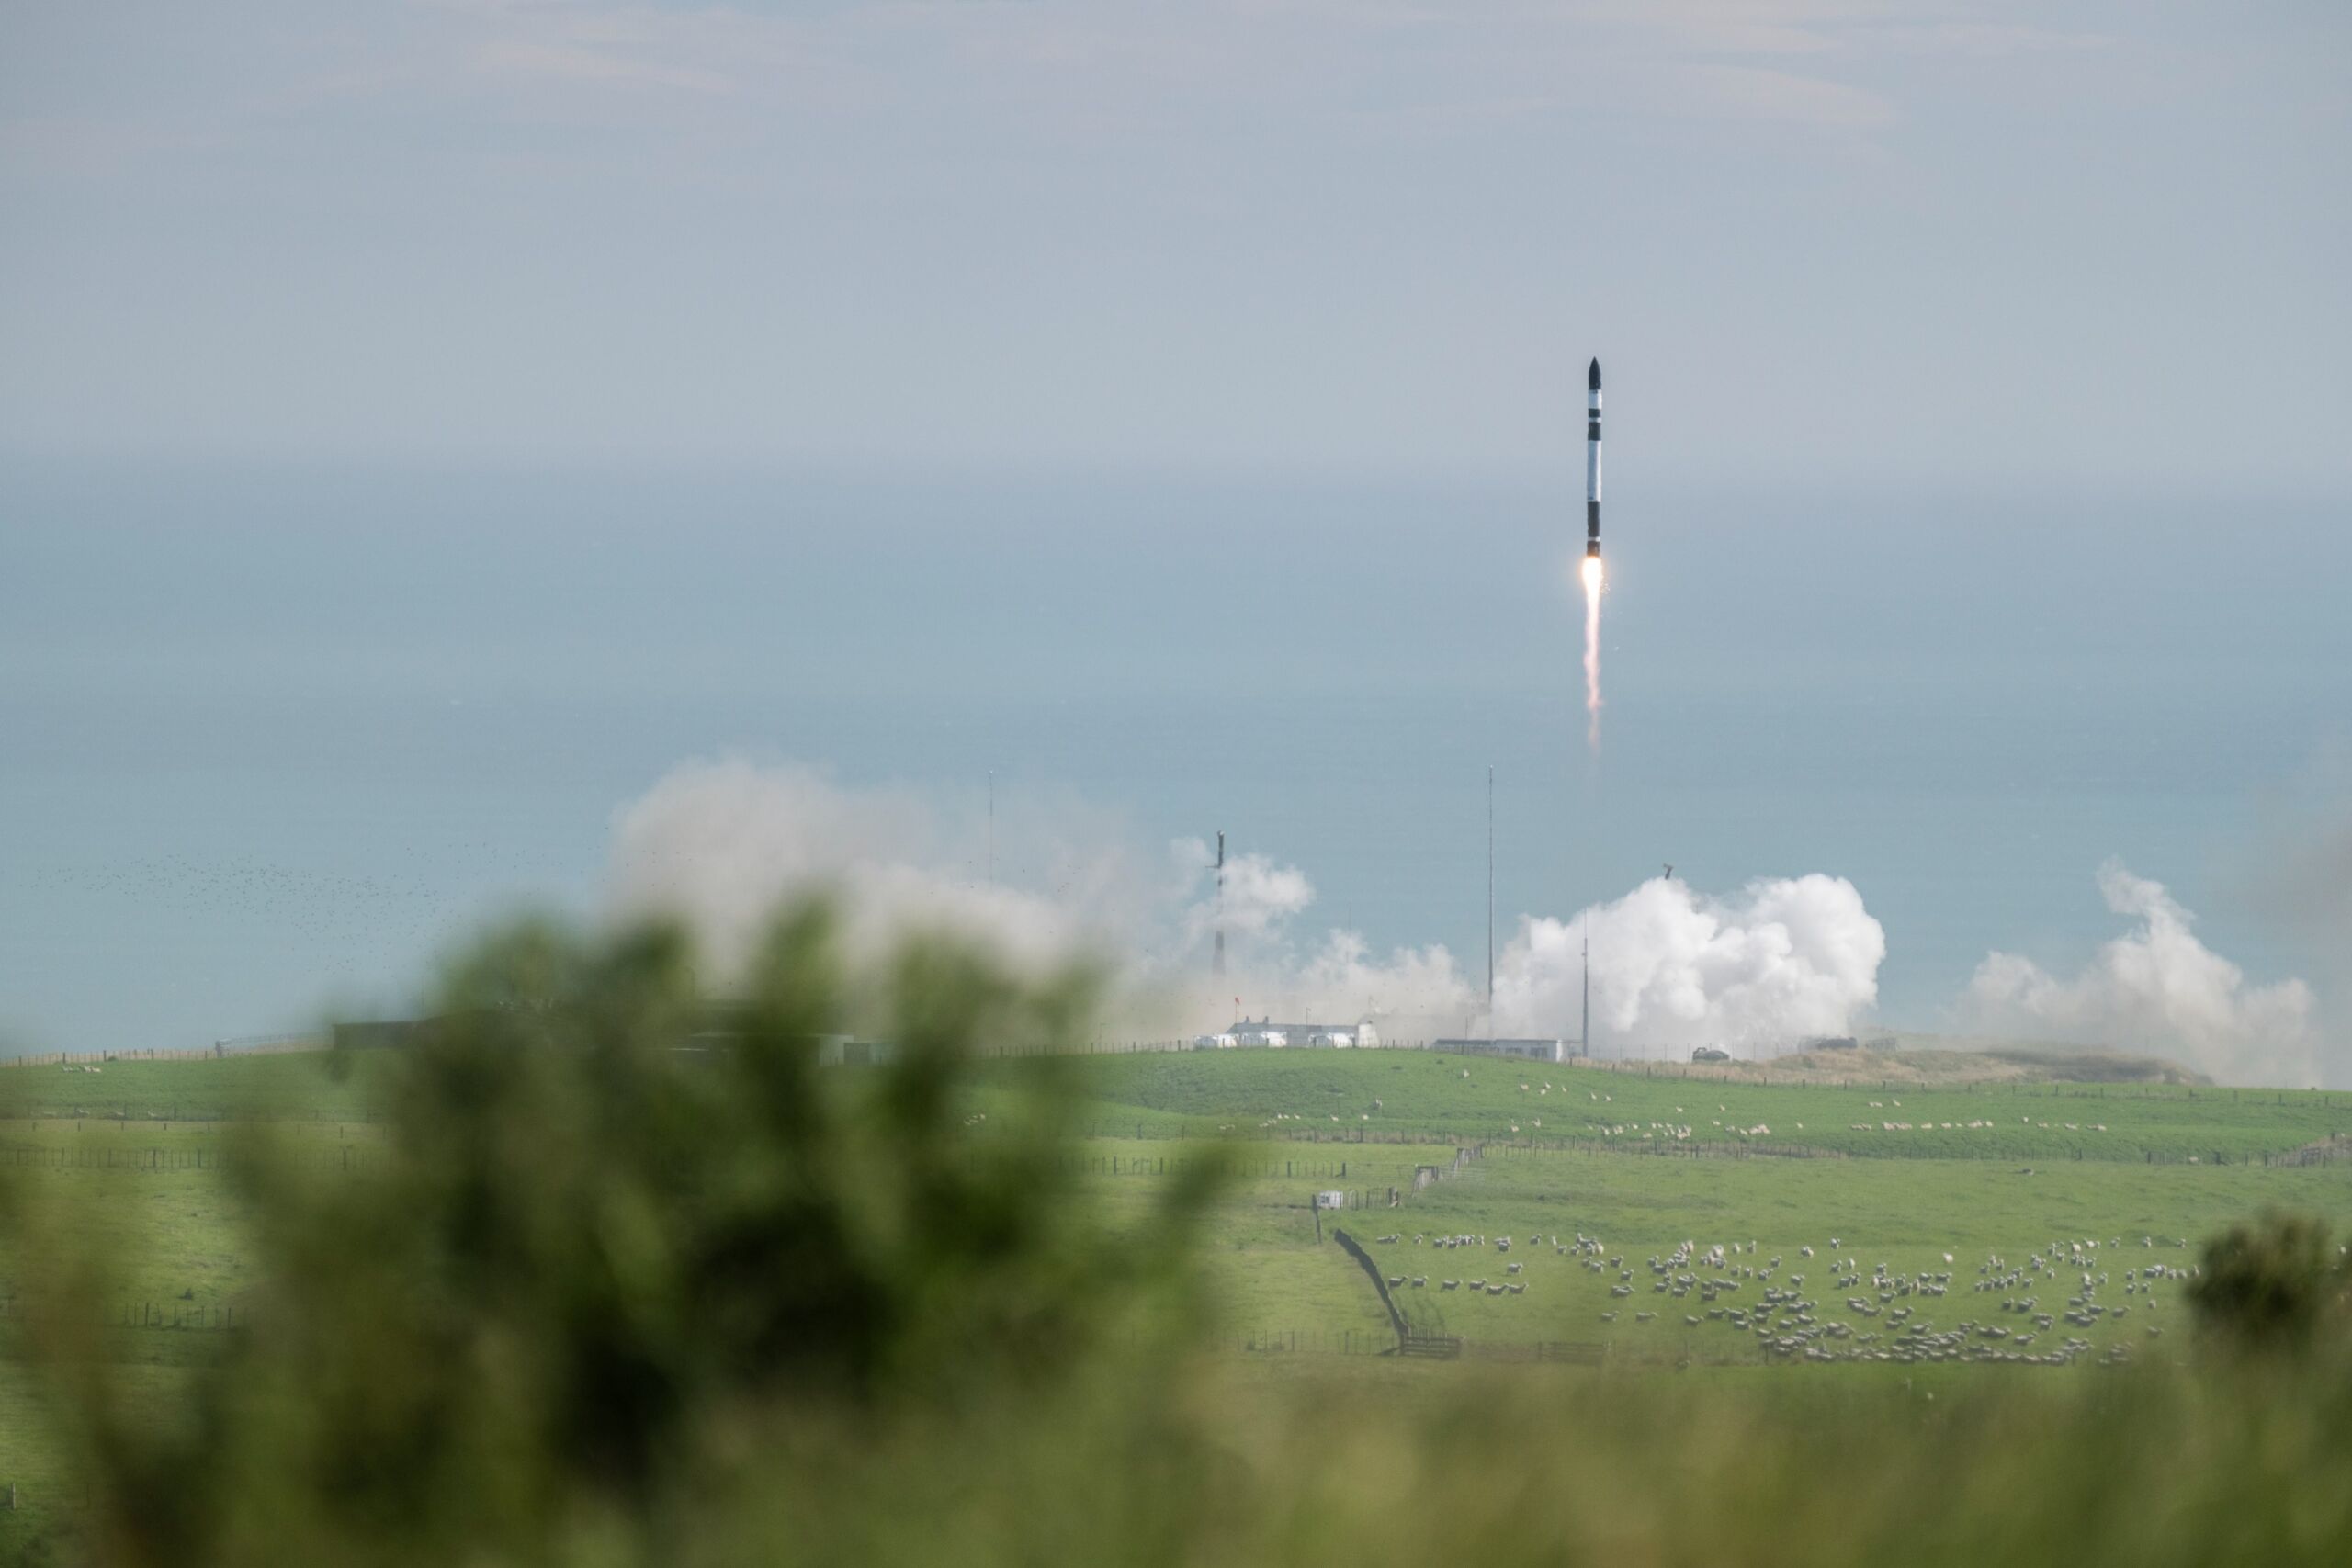
Enlarge/ Electron returned to flight successfully this week. (credit: Rocket Lab)
Welcome to Edition 6.24 of the Rocket Report! This will be the final edition of this newsletter until January 4—hey, space enthusiasts need a holiday break too! And given all that’s expected to happen in 2024 in the world of launch, a bit of a recharge seems like a smart move. Stephen and I wish everyone happy holidays and a healthy and prosperous new year. Until then!
As always, we welcome reader submissions, and if you don’t want to miss an issue, please subscribe using the box below (the form will not appear on AMP-enabled versions of the site). Each report will include information on small-, medium-, and heavy-lift rockets as well as a quick look ahead at the next three launches on the calendar.
Ranking the top 10 US launch companies of 2023. Oops, we did it again and published a list of the most accomplished US commercial launch companies. It’s no surprise that SpaceX is atop the list, but what comes after is more intriguing, including a new company in second position. I hope the list sparks debate, discussion, and appreciation for the challenge of operating a successful rocket company.
The latest Apple Watch’s big main draw was the double tap gesture control, but now the wearables maker is performing a more lethal kind of double tap on its latest Series 9 watches and premium Ultra 2 device. The company has already taken the device down from its online store, and in just two days, you’ll be cut off…
Tesla has issued a second recall in the US in as many weeks. This time around, it’s recalling 120,423 Model S and X vehicles made between 2021 and 2023 due to an issue that may result in an unlocked door unlatching and opening during a crash. According to the National Highway Traffic Safety Administration (NHTSA), this increases the risk of injury and means that the EVs fail to comply with a federal safety regulation. The automaker has already issued a free over-the-air (OTA) update to resolve the problem and owner notification letters are expected to go out in February.
Earlier this month, Tesla recalled more than 2 million EVs over Autopilot safety concerns. The company issued a free OTA update with features that aim to make sure drivers are paying attention while using the system.
This article originally appeared on Engadget at https://www.engadget.com/tesla-is-recalling-120000-vehicles-in-the-us-over-a-door-safety-issue-114540716.html?src=rss
You’ll never uncover The Next Great Thing if you don’t deviate from the norm. When looking back at 2023’s laptops, we can see that many were merely refreshed designs—approaches that already work. But what happens when a company explores a design that, though not the most appealing today, might lead us to a new trend tomorrow?
You might end up with some computers that many, or even most, people aren’t currently interested in buying. But you could also end up glimpsing the designs that influence future laptops.
The laptops we’re about to look at all defied trends in some way, and we’re curious to see if they impact the laptop industry beyond 2023. We’ll also look at the challenges these ideas might face in the future—and some ways they could improve.
Motorsport fans who yearn for juicy behind-the-scenes insights might want to circle January 2 on their 2024 calendar. The third season of Formula E’s unscripted reality show Unplugged will hit the Roku Channel on that date. It’s the first time that the show will be available on Formula E’s new streaming home, while fans around the world will be able to check it out on YouTube.
Unplugged will arrive on Roku just 11 days before the motorsport’s tenth season starts with the Mexico E-Prix on January 13. That race will also stream on Roku as the platform ventures into live sports.
The latest season of Unplugged follows the events of the 2022-23 Formula E campaign, including a title race that was only decided on the final weekend. Along with the twists and turns and personal drama, the eight-episode season will also highlight some of the motorsport’s tech advancements, such as the new Gen3 racecar that drivers had to get to grips with.
In case you need a refresher of what happened in Formula E’s last campaign (or you just want to rewatch all the action), it’s worth noting that every race from the motorsport’s first nine seasons is available to stream on its website. Every Season 10 race will be available on that platform too, albeit one week after each event. Along with Roku, races will air live on Paramount+ and CBS this season.
This article originally appeared on Engadget at https://www.engadget.com/formula-es-version-of-drive-to-survive-will-hit-roku-in-january-102516767.html?src=rss
In 2005, the reclassification of pseudoephedrine to behind-the-counter status led to widespread use of oral phenylephrine in OTC decongestants, despite evidence of its ineffectiveness. Randy Hatton, a clinical professor in the College of Pharmacy at the University of Florida, and his colleague worked to bring this issue to the FDA’s attention, revealing loopholes in the regulatory process for older OTC drugs. Hatton writes in an opinion piece for Scientific American: Before the FDA required that drugs had to be proven effective, it determined whether OTC drugs were effective through expert panels that reviewed existing data. These OTC monographs establish what older OTC ingredients can be marketed without FDA approval. The oral decongestant monograph panel reviewed a few published studies and multiple unpublished studies for phenylephrine. Of the unpublished studies, only four studies showed oral phenylephrine was effective, while seven showed it was no better than placebo. We requested copies of all evidence used by the nasal decongestant review panel via a Freedom of Information Act request and performed a systematic review and meta-analysis ourselves. […]
The FDA has multiple regulatory processes for different types of medicinal compounds. People are perhaps most familiar with the New Drug Application process, which leads to clinical trials for prescription drug approvals. However, many OTC or nonprescription drugs are regulated differently. In fact, a law passed in 1951, the Durham-Humphrey Amendment to the 1938 Food, Drug, and Cosmetic Act, created the categories of prescription and nonprescription drugs. In 1962, the act was amended again so that drugs had to be shown to be effective, hence the requirement for well-done clinical trials. But what about the drugs that were approved before 1962? This is the loophole that some OTC drugs fall through. For prescription drugs, FDA tried to address pre-1962 approvals through a review of over 3,000 prescription drugs. Most of those drugs have now been reviewed and addressed, but there are still unapproved prescription drugs on the market today, such as an extended-release form of oral nitroglycerin. For nonprescription drugs, FDA established the OTC monograph process 10 years after the 1962 amendment to the Food, Drug, and Cosmetic Act, which required products not proven effective to be reconsidered. FDA formed advisory panels grouping hundreds of ingredients into 26 categories based on the products’ uses. After gathering all available information, both published and unpublished, from manufacturers, the advisory panels issued final reports to FDA about whether these ingredients were GRASE (generally recognized as safe and effective), not GRASE, or inconclusive. GRASE ingredients can be used in nonprescription drugs without FDA approval if the use matches the monograph. “The oral phenylephrine example shows that FDA needs more funding to look at these old drugs,” concludes Hatton. “We need public funds to support independent researchers who want to examine these products objectively. The government should be able to spend millions to save consumers billions on ineffective products. Companies that market these products have no incentive to prove they don’t work. Nonprescription drugs must be effective — not just safe.”
If you’d previously purchased Discovery shows from the PlayStation Store, you can breathe easily now. Sony has announced that it’s no longer removing shows from the network by December 31 like it had previously planned, thanks to updated licensing agreements. Earlier this month, the company said that it’s pulling Discovery shows from PlayStation and is even removing any purchased title from your library due to content licensing agreements with its providers. The Discovery shows available on the PlayStation Store include MythBusters, Deadliest Catch and Cake Boss.
In all, around 1,200 titles would’ve been affected by the change, and you wouldn’t have gotten a refund for any of them. The announcement came shortly after Warner Bros Discovery, the owner of Discovery Channel, had revealed in an earnings report that its flagship streaming service Max lost 2.5 million subscribers over a six month period.
Both of Sony’s announcements were brief and didn’t elaborate on its licensing troubles with the network. As The New York Times said when the company published the warning that it was going to remove any Discovery show you’d purchased in the past, though, the situation raised questions about the meaning of ownership in the age of digital goods. Supposedly, buying digital would give you access to a piece of content forever, since there’s no physical medium that could break or get lost. As this incident demonstrates, that’s not true at all, and you could only hope that networks and providers never change their licensing deals.
This article originally appeared on Engadget at https://www.engadget.com/sony-wont-take-away-your-playstation-bought-discovery-shows-after-all-083239866.html?src=rss
An anonymous reader quotes a report from the Los Angeles Times: It was the late 1980s when Gary Mund felt his pinky tremble. At first it seemed like a random occurrence, but pretty quickly he realized something was seriously wrong. Within two years, Mund — a crew worker with the Eastern Municipal Water District in Riverside County — was diagnosed with Parkinson’s disease. The illness would eventually consume much of his life, clouding his speech, zapping most of his motor skills and taking away his ability to work and drive. “It sucks,” said Mund, 69. He speaks tersely, because every word is a hard-won battle. “I was told the herbicide wouldn’t hurt you.”
The herbicide is paraquat, an extremely powerful weed killer that Mund sprayed on vegetation as part of his job from about 1980 to 1985. Mund contends the product is responsible for his disease, but the manufacturer denies there is a causal link between the chemical and Parkinson’s. Paraquat is manufactured by Syngenta, a Swiss-based company owned by the Chinese government. The chemical is banned in at least 58 countries — including China and Switzerland — due to its toxicity, yet it continues to be a popular herbicide in California and other parts of the United States. But research suggests the chemical may cross the blood-brain barrier in a manner that triggers Parkinson’s disease, a progressive, neurodegenerative disorder that affects movement. Now, Mund is among thousands of workers suing Syngenta seeking damages and hoping to see the chemical banned.
Since 2017, more than 3,600 lawsuits have been filed in state and federal courts seeking damages from exposure to paraquat products, according to Syngenta’s 2022 financial report (PDF). […] Paraquat is 28 times more toxic than another controversial herbicide, Roundup, according to a report from the Pesticide Action Network. (Roundup has been banned in several parts of California, including a 2019 moratorium by the Los Angeles County Board of Supervisors forbidding its use by county departments.) Paraquat also has other known health effects. It is listed as “highly toxic” on the U.S. Environmental Protection Agency’s website, which says that “one small sip can be fatal and there is no antidote.” The EPA is currently reviewing paraquat’s approval status. However, both the EPA and Syngenta cited a 2020 U.S. government Agricultural Health Study that found there is no clear link between paraquat exposure and Parkinson’s disease. A 2021 review of reviews similarly found that there is no causal relationship.